Category: Regulation D
Closing a capital raise feels like a finish line, but for issuers operating under federal exemptions, it is really just the starting point of an ongoing responsibility. Annual Blue Sky compliance maintenance is the process of meeting continuing state-level securities obligations after your initial offering is complete. It covers everything from renewing notice filings and paying state fees to tracking jurisdiction-specific deadlines that change from year to year.
If you raised capital through Reg D, Reg A, or Reg CF, the states where your investors reside may require you to file paperwork, pay renewal fees, or submit updated disclosures on a recurring basis. Missing these obligations is not a technicality. It can expose your business to regulatory penalties, disrupt future fundraising, and erode the trust of the investors you worked hard to bring on board.
This guide explains what annual Blue Sky compliance maintenance involves, how requirements vary by offering type and state, and what issuers can do right now to stay on track.
What Is Annual Blue Sky Compliance Maintenance?
Annual Blue Sky compliance maintenance refers to the ongoing state-level filing and renewal obligations that issuers must fulfill after completing a securities offering. Each U.S. state has its own securities laws, commonly known as Blue Sky laws, and many require issuers to take action on a recurring basis, not just at the time of the initial offering. These ongoing obligations can include renewing notice filings, paying annual fees, submitting updated investor disclosures, and notifying state regulators of material changes in the offering. The specific requirements vary widely depending on the state, the type of exemption used, and whether the offering is still active or has closed. It is important to understand that compliance does not end when the last investor check clears. State regulators expect issuers to remain current throughout the life of the offering and, in many cases, for a period following its close. Issuers who treat Blue Sky compliance as a one-time task often find themselves out of compliance without realizing it. The annual maintenance process is also distinct from the initial filing requirements under Reg A, Reg D, and Reg CF. Initial filings establish the right to offer securities in a given state. Annual maintenance preserves that right and satisfies the state's ongoing regulatory expectations.Why Ongoing State Compliance Matters for Issuers
The consequences of failing to maintain annual state filings are more serious than many issuers expect. State securities regulators have the authority to issue cease-and-desist orders, impose fines, and require rescission of securities sold to investors in their jurisdiction. In some states, selling securities without proper registration or a maintained exemption is a criminal offense. While state regulators do monitor compliance, enforcement across all 50 states and U.S. territories involves distinct roles for federal and state authorities. The SEC enforces federal securities laws at the national level, while individual state regulators enforce local "Blue Sky" laws. To maintain compliance, state examiners regularly audit issuer records, review portal filings, and cross-reference federal disclosures with state records. Consequently, an issuer that falls behind on annual Blue Sky filings may not receive an early warning, remaining unaware of the oversight until a formal notice of violation arrives. Consistent compliance also signals credibility. Investors in Reg A and Reg D offerings are often retail investors who rely on the regulatory framework for protection. Maintaining your Blue Sky filings shows those investors that your business takes its legal obligations seriously, which matters when building long-term relationships in capital markets.Key Annual Filing Requirements by Offering Type
Annual Maintenance for Reg D Issuers
Reg D offerings rely on Form D filed with the SEC, but that federal filing is only part of the picture. Most states require issuers to submit a separate state notice filing, often called a Blue Sky notice filing or state Form D, to qualify the offering in each jurisdiction where investors reside. Many of those state filings are not one-time submissions. A significant number of states require annual renewal of Reg D notice filings as long as the offering remains active. Some states, including California and New York, have specific renewal timelines and associated fees that must be tracked carefully. California, for example, requires issuers to renew their exemption filings annually and charges fees tied to the amount raised in that state, and New York is typically every 4 years. Form D amendments at the federal level are required when material information changes, such as a new first sale date or a significant increase in the total offering amount. At the state level, some jurisdictions require issuers to file an amendment whenever the federal Form D is amended, while others have independent triggers. Tracking these state-specific deadlines manually is one of the most common sources of compliance gaps for Reg D issuers. A practical approach is to build a compliance calendar at the start of the offering that maps every state filing, renewal date, and fee payment to a specific deadline. Updating that calendar whenever a new investor is added from a previously unrepresented state is equally important.Annual Maintenance for Reg A Issuers
Reg A offerings come in two tiers, and that distinction directly affects annual state compliance obligations. Tier 1 offerings, which allow issuers to raise up to $20 million in a 12-month period, are subject to full state review and registration in each state where securities are sold. Tier 2 offerings, which allow up to $75 million, preempt most state registration requirements but do not eliminate all state obligations. For Tier 1 issuers, annual compliance can be substantial. Each state where you have registered the offering may require annual renewal filings, updated financial disclosures, and fee payments. These obligations continue for as long as the offering remains qualified in that state. Managing multi-state compliance calendars for a Tier 1 Reg A offering can involve dozens of active jurisdictions at any given time. Tier 2 issuers face fewer state filing requirements, but they are not exempt from all Blue Sky obligations. Some states still require notice filings and fees even for Tier 2 offerings. Issuers also must continue to meet federal ongoing disclosure requirements under Regulation A, including annual reports on Form 1-K and semiannual reports on Form 1-SA. These federal filings often trigger parallel state notice obligations. For issuers managing multi-state Reg A compliance, building a jurisdiction-by-jurisdiction calendar with clear renewal windows, contact information for state regulators, and fee schedules is the most reliable way to avoid gaps, which can be a very complicated process. This is an area where working with a specialized compliance partner can significantly reduce both administrative burden and legal risk. While the specific requirements ultimately depend on the state, the table below highlights the general compliance responsibilities issuers can expect under Reg D, Reg A, and Reg CF.| Compliance Requirement | Reg D | Reg A Tier 1 | Reg A Tier 2 | Reg CF |
| Initial state filing required | Yes | Yes | Notice filings in certain states | Notice filings where applicable |
| Annual state renewals | Often required for active offerings | Commonly required | May apply in certain states | Limited and state-dependent |
| Ongoing SEC reporting | No | No | Yes (Forms 1-K, 1-SA, 1-U) | Yes (Form C-AR while reporting obligations continue) |
| State filing fees | Yes | Yes | May apply | May apply |
| State-specific amendments | May be required | Commonly required | May be required | May be required where notice filings apply |
| Multi-state compliance complexity | High | High | Moderate | Low to Moderate |
Annual Maintenance for Reg CF Issuers
million from the public through SEC-registered funding portals. Because these offerings are conducted through registered intermediaries, many issuers assume that the portal handles every state compliance obligation. That assumption is only partly correct. Federal law generally preempts states from requiring full registration of a qualifying Reg CF offering. However, a state notice filing may be triggered when the issuer’s principal place of business is located in a state that requires such a filing. A filing may also be triggered in another state if residents of that state purchase more than 50% of the aggregate amount of the offering. The requirement applies only where the relevant state has adopted a Reg CF notice filing requirement. These filings are generally coordinated with the issuer’s Form C submission. Issuers should therefore identify any triggered states before launch, prepare the required notice forms and fees, and submit the applicable state filings at the same time as the Form C. Ongoing state obligations are usually lighter than those associated with Reg D or Reg A, but they may still include amendments, renewals, sales reports, or closing notices in certain jurisdictions. Issuers should also maintain accurate offering records, monitor material changes, and confirm whether any follow-up filing is required while the offering remains active. Small businesses using Reg CF often do not have dedicated legal or compliance staff. In that case, working with a compliance service that tracks state-specific Reg CF requirements can help prevent filing gaps and ensure that both initial and ongoing obligations are handled properly.State-by-State Variations in Annual Compliance Requirements
One of the most common misconceptions about Blue Sky compliance is that it works the same way in every state. It does not. Each state has its own securities division, its own fee schedule, and its own renewal timeline. What counts as an active offering that requires annual renewal in one state may be treated differently by another. States like California, Texas, and New York are known for stricter annual renewal requirements. California's Department of Financial Protection and Innovation requires Reg D issuers to renew their notice filings annually and submits detailed instructions on the required documentation and fees. Texas requires separate state notice filings for certain exempt offerings and has its own filing portal through the Texas State Securities Board. On the other end of the spectrum, some states have more streamlined processes. Several states accept the federal Form D filing as sufficient notice without requiring a separate state-level filing or annual renewal. However, even in those states, issuers must stay informed about any regulatory changes that could affect their obligations from one year to the next. The practical takeaway is that issuers cannot apply a single compliance template across all states. The only reliable approach is to treat each state as its own compliance jurisdiction with its own rules, deadlines, and contact points. Working with a compliance partner that has deep knowledge of state-specific requirements is not just convenient. For multi-state offerings, it is often the only realistic way to maintain accurate, timely compliance across the board.Common Mistakes Issuers Make With Annual Blue Sky Filings
Even well-intentioned issuers can run into annual Blue Sky compliance issues. Most problems fall into a few predictable categories — and they’re often avoidable with the right process.1. Missed Deadlines
Missed renewal deadlines are the most common issue. Renewal windows vary by state, and many states do not send reminders. An issuer may complete its initial filing, move on, and later discover it is out of compliance simply because no one was tracking the renewal date. Why it matters: Missing a renewal deadline can create immediate compliance risk and lead to added cost, delay, and regulatory issues.- Late fees may apply.
- Some states may require a new filing.
- The issuer can fall out of compliance without warning.
2. Filing Under the Wrong State Classification
Another common mistake is using the wrong filing category or exemption. This can happen when an issuer:- files under the wrong classification
- fails to update the filing after the offering changes
- relies on an exemption that does not actually apply in a particular state
3. Submitting Incomplete Documentation
Incomplete renewal packages are another frequent source of problems. Some states require supporting materials as part of the annual filing, such as:- audited financial statements
- officer certificates
- copies of the offering circular
- Renewal can be delayed.
- The issuer may remain in a compliance gap while the issue is resolved.
4. Overlooking New States
Many issuers treat Blue Sky compliance as a one-time task tied only to the initial offering. That creates risk. If investors later come in from a state not covered by the original filing, the issuer may need to make a notice filing in that state — sometimes retroactively. Why it matters: Failing to account for new states can create additional filing obligations and increase the risk of compliance gaps as the offering expands.- New investor activity can trigger new state filing obligations.
- Investor address tracking needs to be ongoing, not a one-time review.
How a Blue Sky Compliance Partner Supports Annual Maintenance
Managing annual Blue Sky compliance across multiple states is time-consuming, technically complex, and high-stakes. A specialized compliance partner provides the infrastructure, expertise, and ongoing attention that most issuers cannot replicate internally without significant investment. At the core of what a compliance service provides is deadline management. A good partner maintains a live compliance calendar for each client that tracks renewal windows, fee payment dates, and documentation requirements by state. When a renewal deadline approaches, the partner prepares the required filings, calculates the applicable fees, and submits everything on time without requiring the issuer to monitor each state independently. Beyond deadline tracking, compliance partners also manage fees, prepare state-specific filing packages, and stay current with regulatory changes that could affect their clients' obligations. State securities laws change regularly. Fee schedules are updated, new notice requirements are introduced, and procedural rules shift. A compliance partner focused entirely on Blue Sky requirements is far more likely to catch those changes quickly than an in-house team managing compliance as one of many responsibilities. The cost comparison between in-house management and outsourcing is straightforward for most issuers. Building the internal knowledge base, hiring staff with state securities expertise, and maintaining subscriptions to state regulatory updates represents a significant ongoing investment. For most small and mid-sized issuers, the cost of a specialized compliance service is substantially lower than replicating that capability internally, and the risk of error is significantly reduced. Blue Sky Comply provides exactly this kind of support. With expertise across Reg D, Reg A, and Reg CF state compliance, the team manages annual maintenance obligations for law firms, private companies, public companies, funds, and crowdfunded entities, delivering precise, timely filings so issuers can focus on growing their business.How Do You Know If Your Annual Blue Sky Filings Are Up to Date?
Many issuers are not sure whether their annual Blue Sky filings are current. This is more common than you might expect, especially when compliance responsibility has shifted between team members or outside counsel over time. The following checklist provides a practical starting point for auditing your current compliance status. Annual Blue Sky compliance audit checklist:- List every state where you have investors and confirm whether a notice filing was made in that state.
- Review your initial filing records to identify which states required annual renewals and what the renewal timelines are.
- Check the expiration or anniversary dates on all active state filings and confirm whether renewals have been submitted.
- Verify that all required fees have been paid and that no deficiency notices are outstanding with any state securities division.
- Confirm that your Form D at the SEC level is current and that any required amendments have been filed.
- Review investor addresses for any new states that entered your offering after the initial filing period and assess whether new notice filings are needed.
- Check whether any states where you have filed have updated their requirements, fees, or renewal procedures since your last filing.
Frequently Asked Questions
What is annual Blue Sky compliance maintenance and who needs it? Annual Blue Sky compliance maintenance refers to the ongoing state-level filing, renewal, and fee obligations that securities issuers must fulfill after completing an offering under Reg D, Reg A, or Reg CF. Any issuer who has sold securities to investors in one or more U.S. states under a federal exemption may have continuing state compliance obligations that recur on an annual or periodic basis. How often do issuers need to renew their state Blue Sky filings? Renewal frequency varies by state and offering type. Many states require annual renewals for Reg D notice filings and Reg A registrations. Some states tie renewal deadlines to the anniversary of the initial filing, while others operate on a calendar-year cycle. Issuers should review each state's specific requirements to determine the correct renewal schedule for their offering. What happens if an issuer misses an annual Blue Sky filing deadline? Missing a deadline can result in late fees, deficiency notices, or a lapse in the exemption or registration in that state. In more serious cases, state regulators may require the issuer to re-file entirely, or they may initiate an enforcement inquiry. Selling securities in a state without a valid registration or maintained exemption can expose the issuer to civil and, in some cases, criminal liability. Are annual maintenance requirements the same in every state? No. Each state has its own securities laws, renewal procedures, fee schedules, and documentation requirements. Some states require detailed annual renewal packages with financial updates and officer certifications. Others accept a simple fee payment or no renewal at all. Issuers must track requirements on a state-by-state basis. Do Reg D issuers need to file annual amendments in all states where they sold securities? Not necessarily in all states, but many states do require annual renewal of Reg D notice filings for active offerings. The obligation depends on whether the offering is still open and on each state's specific rules. Issuers should review the requirements for every state where they have investors and maintain a filing calendar accordingly. How does annual Blue Sky maintenance differ for Reg A versus Reg CF offerings? Reg A offerings, especially Tier 1, involve more extensive state compliance obligations because they require state-level registration or notice filings in each investor jurisdiction. Tier 2 offerings preempt most state registration requirements but may still require state notice filings in certain jurisdictions. Reg CF offerings benefit from federal preemption of state registration requirements, but some states still assert notice filing rights, making ongoing monitoring necessary even for crowdfunding issuers. Both offerings also allow capital raises from non-accredited investors. And, Reg A allows issuance of free-trading shares. Can small businesses or startups handle annual Blue Sky compliance without outside help? It is technically possible but carries significant risk. Annual Blue Sky compliance involves tracking multiple state deadlines, preparing jurisdiction-specific filings, and staying current with regulatory changes across many states. Small businesses without dedicated compliance staff frequently miss deadlines or make filing errors that create legal exposure. Partnering with a specialized compliance service like Blue Sky Comply is a cost-effective way for smaller issuers to maintain accurate, timely compliance without building that capability internally. This content is for informational purposes only and does not constitute legal, financial, investment, or tax advice, or a recommendation to buy or sell any security. No attorney-client relationship is created by your use of this blog. Please consult qualified professionals regarding your specific situation.
When a company decides to raise capital, one of the first decisions it faces is choosing the right SEC exemption. Two of the most commonly used options are Reg A and Reg D. Each one comes with its own rules, costs, timelines, and investor access requirements. Understanding how they differ can save companies significant time and money, and help them avoid compliance problems down the road. This guide breaks down the key differences between Reg A and Reg D offerings so you can make a more informed decision for your capital raise.
Understanding Regulation A Offerings
Regulation A gives companies a way to raise capital from the public without going through a full IPO. It offers two tiers based on how much a company wants to raise. Tier 1 allows offerings up to $20 million within a 12-month period, while Tier 2 raises that ceiling to $75 million. Both tiers require SEC qualification, but they differ significantly when it comes to state compliance and reporting obligations. Unlike a traditional IPO, Reg A offerings are generally faster to execute and require less regulatory burden. Still, they involve more preparation than most private placements. Companies need to file an offering circular with the SEC and wait for qualification before they can begin accepting investments. For many mid-sized companies, Reg A Tier 2 is particularly attractive because it offers broad investor access while staying below the full public company reporting threshold.Who Can Invest in Reg A Offerings?
One of the biggest draws of Regulation A offerings is that they are open to all investors, not just accredited ones. Any member of the public can invest, which gives issuers access to a much wider pool of potential backers. This makes Reg A a popular choice for companies that want to build community ownership or run consumer-facing fundraising campaigns. That said, Tier 2 does include some protections for non-accredited investors. Under Tier 2, non-accredited investors are limited to investing no more than 10% of the greater of their annual income or net worth in any single Reg A offering. Accredited investors are not subject to this cap. These limits are designed to protect everyday investors from putting too much of their savings into a single offering.State Blue Sky Compliance Requirements for Reg A
Blue Sky compliance is one of the more complex parts of a Reg A offering, and it varies depending on which tier you are using. Tier 1 offerings must comply with state Blue Sky laws in every state where securities are offered or sold. That means navigating separate registration requirements across multiple jurisdictions, which can be time-consuming and expensive. Tier 2 offerings are federally preempted from state registration requirements, which significantly reduces the compliance burden for issuers selling in multiple states. However, this does not mean states are completely out of the picture. Issuers still need to submit notice filings and pay filing fees in each state where they conduct their offering. Working with a Blue Sky compliance specialist can help issuers manage these requirements efficiently across all target states.Understanding Regulation D Offerings
Regulation D is the most widely used capital raising exemption in the United States. It covers several rules, but Rule 506(b) and Rule 506(c) are the ones most companies rely on. Reg D offerings are private placements, meaning they are not open to the general public in the same way that Reg A offerings are. In exchange, they come with far fewer regulatory requirements and can be completed much faster. Rule 504 also falls under Reg D but is less commonly used, as it only permits raises up to $10 million and does not carry federal preemption from state registration. For most serious capital raises, companies focus on Rule 506(b) or 506(c). Both allow unlimited capital raising with no SEC-imposed dollar cap, making them appealing to companies at various stages of growth.Accredited Investor Requirements Under Reg D
Regulation D offerings, particularly under Rule 506(b) and 506(c), are primarily designed for accredited investors. To qualify as an accredited investor, an individual must have earned more than $200,000 annually (or $300,000 jointly with a spouse) for the past two years, or hold a net worth exceeding $1 million, not counting the value of their primary residence. Rule 506(b) allows up to 35 sophisticated non-accredited investors to participate alongside accredited investors, as long as there is no general solicitation or advertising. Rule 506(c) removes that option entirely and requires all investors to be verified accredited investors. Under Rule 506(c), issuers must take reasonable steps to verify accredited status, which often means collecting tax returns, bank statements, brokerage account records, or using a third-party accredited investor verification service.Blue Sky Implications for Reg D Offerings
Rule 506(b) and 506(c) offerings benefit from federal preemption under the National Securities Markets Improvement Act (NSMIA), which means issuers do not need to register their securities at the state level. This is a major advantage for companies raising capital from investors across multiple states. However, federal preemption does not eliminate state involvement entirely. Issuers are still required to file Form D notice filings with each state where securities are sold, and they must pay the applicable filing fees. These filings are typically straightforward, but deadlines vary by state, and missed filings can result in penalties. Many issuers work with compliance professionals to track these requirements and ensure filings are submitted on time across all relevant jurisdictions.Reg A vs. Reg D at a Glance
Before exploring each exemption in more detail, it helps to see how Regulation A and Regulation D compare across the areas that matter most to issuers. The table below provides a high-level overview of their key differences, including investor eligibility, compliance requirements, fundraising limits, and typical use cases. Use this table immediately after the introduction and before “Understanding Regulation A Offerings.” It gives readers a concise overview before the article explains each exemption in detail.| Feature | Regulation A | Regulation D |
| Offering type | Exempt public offering | Private placement |
| Maximum raise | Up to $20 million under Tier 1 or $75 million under Tier 2 | No SEC-imposed limit under Rule 506(b) or Rule 506(c) |
| Eligible investors | Accredited and non-accredited investors | Primarily accredited investors |
| General solicitation | Permitted after SEC qualification | Prohibited under Rule 506(b); permitted under Rule 506(c) |
| SEC process | Form 1-A filing and SEC qualification required | Form D notice filing after the first sale |
| Blue Sky treatment | Tier 1 generally requires state qualification; Tier 2 is federally preempted but may require state notices and fees | Rule 506 offerings are federally preempted but require state notice filings and fees |
| Ongoing SEC reporting | Required for Tier 2 issuers | Generally not required |
| Financial statements | Audited financial statements required for Tier 2 | Generally not required by Regulation D |
| Typical timeline | Often several months | Often a matter of weeks |
| Typical cost | Higher due to SEC review, audits, legal work, and state compliance | Lower because qualification and periodic reporting are generally not required |
| Best suited for | Public-facing raises seeking broad investor access | Faster private raises, often from accredited investors |
Disclosure and Reporting Obligations Compared
The reporting requirements between Reg A and Reg D are significantly different, and this is one of the most important distinctions for companies to understand before choosing an exemption. Reg A Tier 2 issuers are required to file ongoing reports with the SEC, similar in structure to the obligations of smaller public companies. These include annual audited financial statements on Form 1-K, semi-annual reports on Form 1-SA, and current event disclosures on Form 1-U when material events occur. Reg D offerings, by contrast, carry minimal ongoing reporting obligations. Once the initial Form D is filed with the SEC within 15 days of the first sale, there are no mandatory periodic filings required. Some issuers voluntarily share updates with investors to maintain relationships and fulfill any information rights they have agreed to in their investor agreements, but this is not a regulatory requirement. For companies that want to avoid the administrative overhead of ongoing reporting, Reg D is clearly the lighter-lift option.Capital Raising Limits and Timeline Considerations
The difference in capital raising limits and timelines between Reg A and Reg D is one of the most practical factors companies weigh when choosing an exemption. Reg A Tier 2 allows a company to raise up to $75 million in a 12-month period, which is well-suited for mid-sized raises where the goal is to access a large number of investors. Tier 1 caps out at $20 million annually and comes with more state-level compliance complexity. Reg D offerings under Rules 506(b) and 506(c) have no statutory dollar cap. A company could raise $5 million or $500 million under the same exemption framework, which makes Reg D appealing across a wide range of deal sizes. The execution timeline is another major differentiator. Reg A offerings typically take 4 to 6 months from initial filing to qualification, including SEC review and comment periods. Reg D offerings can often be launched within a matter of weeks, making them the better choice when speed is a priority.Cost Comparison Between Reg A and Reg D
Cost is often one of the deciding factors between Reg A and Reg D, particularly for early-stage companies with limited budgets. Reg A offerings involve meaningful upfront costs. Legal fees for drafting the offering circular, SEC filing fees, independent audit fees, and state notice filing costs can collectively range from $100,000 to $500,000 depending on the complexity of the offering and how many states are involved. Reg D offerings are considerably more affordable. Total costs typically fall between $25,000 and $100,000, covering legal preparation of the private placement memorandum, SEC Form D filing, and state notice filings. Rule 506(c) offerings may add some expense for accredited investor verification services, but even with that included, Reg D remains the more budget-friendly option. For companies with tighter resources or those testing investor appetite before a larger raise, Reg D offers a more accessible entry point.Which Exemption Is Right for Your Capital Raise?
Choosing between Reg A and Reg D comes down to a few key questions: How much do you want to raise? Who do you want to raise from? How fast do you need the capital? And how much can you spend on compliance? If your goal is to reach retail investors, build community ownership, or run a public-facing campaign, Reg A is likely the better fit despite its higher costs and longer preparation time. If you are raising from a defined network of accredited investors and want to move quickly without heavy compliance overhead, Reg D is usually the smarter choice. Rule 506(b) works well for relationship-based raises where you already know your investors. Rule 506(c) opens the door to general solicitation and advertising, which is useful for broader marketing-driven campaigns targeting verified accredited investors.Combining Exemptions for Strategic Advantage
Some companies choose to use both exemptions at different stages of their growth. A common approach is to launch a Reg D offering first to raise initial operating capital, build a track record, and establish a credible valuation. Once the company has some traction and operational history to show, it then moves forward with a Reg A offering to raise a larger round from a broader investor base. This sequential strategy allows companies to generate momentum before taking on the complexity of a Reg A qualification process. It also means the company arrives at the Reg A stage with financial statements, investor materials, and a business narrative that has already been tested in the market. For companies with long-term capital raising plans, combining exemptions can be a practical and cost-effective path forward.Frequently Asked Questions
Can a company conduct both a Reg A and Reg D offering simultaneously? Generally, yes, but issuers must be careful about integration rules. The SEC may treat two concurrent offerings as a single offering if they are closely related in timing, investor base, and purpose. Companies considering running both at the same time should work with securities counsel to structure the offerings in a way that avoids integration issues. What are the financial audit requirements for Reg A Tier 2 offerings? Reg A Tier 2 issuers are required to include audited financial statements in their offering circular filed with the SEC. These must be prepared by an independent auditor. After the offering is qualified, issuers must continue filing annual audited financials on Form 1-K as part of their ongoing reporting obligations. Do Reg D Rule 506(b) offerings allow any form of public advertising? No. Rule 506(b) prohibits general solicitation and general advertising. This means companies cannot advertise the offering through social media, websites, press releases, or public events. Outreach must be limited to individuals with whom the issuer has a pre-existing and substantive relationship. How long does it typically take to complete Blue Sky filings for multi-state offerings? For Reg D offerings, state Form D notice filings are generally straightforward and can be completed within a few days to a couple of weeks per state, depending on each state's requirements and processing times. For Reg A Tier 1 offerings, where full state registration may be required, the process can take considerably longer. Working with a Blue Sky compliance service helps ensure accurate and timely filings across all target states. What happens if a Reg A offering fails to reach its minimum funding target? If a Reg A offering includes a minimum offering amount and that target is not reached by the deadline, the issuer is typically required to return all funds to investors. Offering circulars must clearly disclose the minimum threshold and the terms under which refunds will be made. Escrow arrangements are commonly used to hold investor funds until the minimum is met. Are there restrictions on reselling securities purchased through Reg A or Reg D offerings? Securities purchased through Reg A offerings are generally not restricted and can be resold freely, which is one of Reg A's key advantages over private placements. Securities purchased through Reg D offerings are restricted securities and generally cannot be resold for at least six months to one year without registration or a valid exemption, such as Rule 144. Which states have the most complex Blue Sky compliance requirements? California, New York, and Texas are generally considered among the most complex states for Blue Sky compliance due to their detailed review processes, specific filing requirements, and in some cases, merit review authority. States like California's Department of Financial Protection and Innovation (DFPI) have their own substantive standards that can add time and cost to offerings that include California residents. Working with a firm that specializes in state securities compliance can help navigate these requirements efficiently. Blue Sky Comply specializes in Blue Sky compliance for Reg A and Reg D offerings, helping issuers manage state filing requirements across all U.S. jurisdictions with accuracy and efficiency. This content is for informational purposes only and does not constitute legal, financial, investment, or tax advice, or a recommendation to buy or sell any security. No attorney-client relationship is created by your use of this blog. Please consult qualified professionals regarding your specific situation.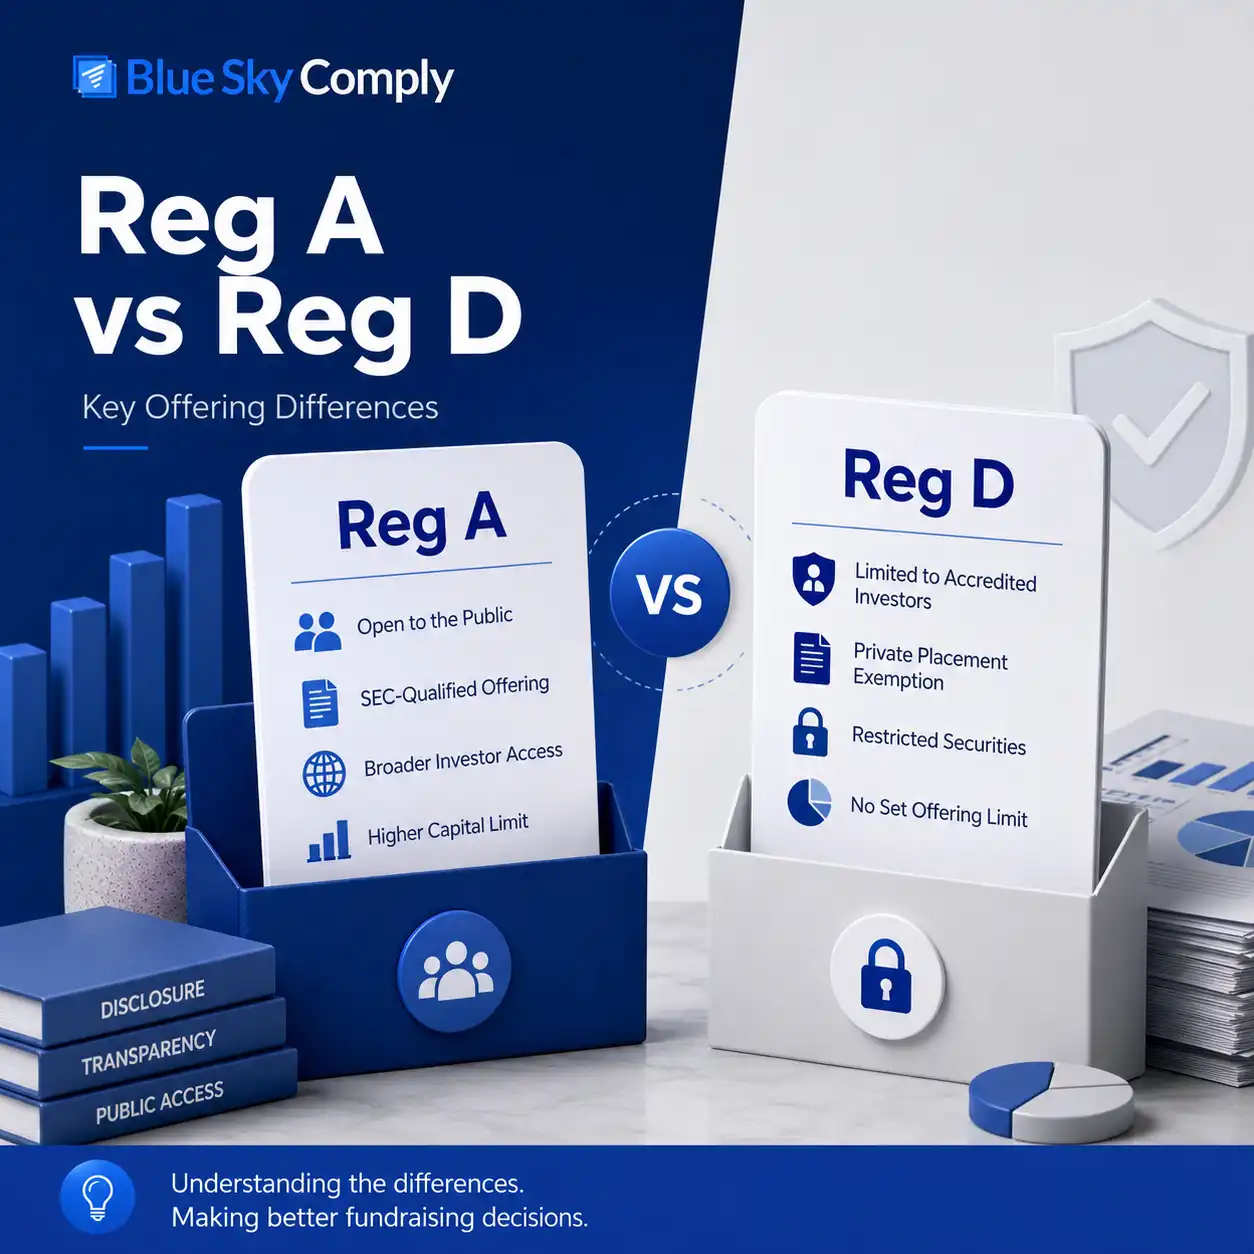
Raising capital involves more than complying with federal securities laws. While many companies focus on SEC requirements, state securities laws continue to have a greater impact on compliance, state fee exposure risks, and the timeliness of raising capital. These regulations, commonly known as Blue Sky Laws, exist alongside federal rules and often require additional filings, fees, or registrations before securities can be sold within a state.
For issuers conducting private placements, Regulation A offerings, or other exempt transactions, overlooking state requirements can lead to missed deadlines, regulatory penalties, and unnecessary delays. Understanding how Blue Sky Laws work is essential to planning a successful securities offering.
This guide explains what Blue Sky Laws are, how they interact with federal securities regulations, which offerings they affect, and why companies raising capital should pay close attention to state-level compliance.
Meeting federal SEC requirements does not necessarily eliminate state compliance obligations. Depending on the exemption used and where investors are located, issuers may still need to file and pay fees with the states.
What Are Blue Sky Laws?
Blue Sky Laws are state securities laws that regulate the offer and sale of securities within individual states, and require issuers to make certain disclosures to states whenever conducting capital raises or primary offerings. Their primary purpose is to protect investors by requiring companies to meet certain disclosure, filing, or registration requirements before offering securities to residents of a particular jurisdiction. Although every state has its own securities regulator and laws, the overall objective remains consistent: promoting transparency and reducing fraudulent investment activity.Why Are They Called Blue Sky Laws?
The phrase "Blue Sky Laws" dates back to the early twentieth century. It originated from efforts to stop speculative investment schemes that were said to have "no more substance than the blue sky." While securities markets have evolved significantly since then, the underlying purpose of these laws has remained largely unchanged. Today, they continue to provide an additional layer of investor protection alongside federal securities regulation.What Do Blue Sky Laws Regulate?
Blue Sky Laws cover far more than the registration of securities offerings. Depending on the state and the type of offering, they may also govern:- Notice filings
- Sales commissions
- Registration requirements
- State filing fees
- Broker-dealer licensing
- Other required documentation from officers
- Enforcement against securities fraud
How Blue Sky Laws Work Alongside Federal Securities Laws
One of the biggest misconceptions among first-time issuers is that complying with SEC rules automatically satisfies every legal requirement. In reality, securities offerings are often subject to both federal and state oversight. The SEC establishes nationwide rules governing securities offerings and exemptions, while each state maintains its own securities authority responsible for enforcing state-specific requirements. The relationship between the two can be summarized as follows:| Federal Securities Laws | Blue Sky Laws |
| Administered by the SEC | Administered by individual state regulators |
| Apply nationwide | Apply within each state |
| Govern federal exemptions such as Regulation D, Regulation A, and Regulation Crowdfunding | Govern state registration, notice filings, and other state-specific requirements |
| Establish federal disclosure rules | Establish state compliance obligations |
Which Securities Offerings Are Affected by Blue Sky Laws?
Blue Sky Laws apply differently depending on the type of securities offering. Some offerings receive substantial federal preemption, while others remain subject to extensive state review.Regulation D Offerings
Most private companies raising capital rely on Regulation D exemptions, particularly Rule 506(b) and Rule 506(c). Although these offerings are exempt from state registration requirements under federal law, they still require state notice filings wherever investors reside. Companies must also comply with each state's filing deadlines and applicable filing fees. For issuers raising money from investors in multiple states, managing these filings can quickly become one of the most time-consuming parts of the offering.Regulation A Offerings
Regulation A offerings are divided into two tiers, and each receives different treatment under Blue Sky Laws.- Tier 1 offerings remain subject to state securities review, meaning companies may need to register or qualify their offering separately in every state where securities will be sold.
- Tier 2 offerings benefit from federal preemption, eliminating full state registration requirements. However, many states still require state filings and fees, making state compliance an ongoing consideration even after SEC qualification, with heavy penalties for not complying.
Regulation Crowdfunding
Regulation Crowdfunding, often referred to as Reg CF, receives broader federal preemption than many other exemptions. In most situations, issuers are not required to complete state registration. However, certain states continue to require notice filings under specific circumstances, particularly when the issuer's principal place of business or investor concentration meets defined thresholds. Although the state burden is much smaller than under other exemptions, companies should still confirm whether additional state filings are required before launching an offering.Why Blue Sky Laws Vary by State
Blue Sky Laws are a state-by-state system, not a single national rulebook. While federal securities laws create an overarching framework, each state has the authority to adopt and enforce its own securities requirements. The result is a patchwork of rules that can differ meaningfully from one jurisdiction to the next. What works in one state may not be enough in another. A filing accepted without issue in one jurisdiction might trigger additional notice requirements, supplemental documents, different fee structures, or separate licensing obligations elsewhere. Even the mechanics of compliance—such as deadlines, renewal periods, and filing procedures—can change from state to state. For companies offering securities across multiple jurisdictions, that variation creates more than just administrative work. It introduces a layer of compliance planning that requires close attention to each state’s specific rules. As the number of states involved increases, so does the complexity. Multi-state offerings often require a coordinated approach to avoid missed filings, inconsistent submissions, or unnecessary regulatory risk.How Companies Stay Compliant With Blue Sky Laws
Effective Blue Sky compliance starts well before an offering reaches investors. Companies that handle state compliance successfully usually do so by building it into the offering process from the outset - not by scrambling to address it after federal documents have already been prepared or sales activity has begun. In practice, Blue Sky compliance works best when it is treated as part of the overall transaction strategy. That means identifying state-level obligations early, tracking deadlines carefully, and creating a repeatable process for filings, fees, renewals, and recordkeeping. A practical compliance process often includes:- Identifying the federal exemption relied upon for the offering
- Determining which states have jurisdiction over the transaction
- Preparing the required notice filings and supporting documents for each applicable state
- Submitting filings within each state’s deadline
- Paying the applicable filing fees
- Tracking renewal, amendment, and ongoing filing obligations
- Maintaining organized records throughout the life of the offering
When Professional Blue Sky Compliance Support Makes Sense
Not every offering requires the same level of Blue Sky compliance support. A smaller raise limited to one or two states may be fairly manageable. But once an offering expands across multiple jurisdictions, the compliance demands often become more time-consuming, more technical, and more difficult to track internally. That is typically the point when outside support becomes especially valuable. Professional Blue Sky compliance assistance is often used when companies:- Conduct offerings in multiple states
- Launch a first-time securities offering
- Manage ongoing filings and amendments
- Complete offerings with multiple state notice requirements
- Need to track renewals and jurisdiction-specific filing deadlines
Frequently Asked Questions About Blue Sky Laws
What are Blue Sky Laws?
Blue Sky Laws are state securities laws that govern how securities offerings are conducted within a state. They are designed to protect investors from fraud and misleading investment activity, while also giving states the authority to impose compliance and disclosure/filing requirements on companies raising capital.Do all states have Blue Sky Laws?
Yes. Every state has its own securities laws and regulatory authority, although the specific requirements vary considerably from one jurisdiction to another.Are Blue Sky Laws the same in every state?
No. Each state establishes its own filing procedures, fees, deadlines, and registration requirements.Do Regulation D offerings require Blue Sky filings?
In most cases, yes. Although Rule 506 offerings are exempt from state registration, they still require notice filings and applicable filing fees in states where investors purchase securities, and often in the state of incorporation.Does Regulation A Tier 2 eliminate Blue Sky compliance?
Not entirely. Tier 2 offerings benefit from federal preemption of state registration requirements, but many states continue to require notice filings and filing fees.What happens if a company violates Blue Sky Laws?
Depending on the state and the nature of the violation, consequences may include late fees, administrative penalties, restrictions on future securities sales, enforcement actions, or investor claims.Blue Sky Laws Are a Core Part of Securities Compliance
Blue Sky Laws remain an important part of securities compliance in the United States. Even when federal exemptions apply, companies often still need to meet state-level requirements. For issuers, that means understanding where filings are required, what each state expects, and when deadlines apply. Taking a proactive approach can help reduce delays, limit regulatory risk, and keep an offering moving smoothly. As offerings expand across multiple states, compliance can quickly become more complex. Blue Sky Comply helps issuers manage state filings, fees, renewals, amendments, deficiency inquiries, and filing requirements with confidence.
Companies raising capital under Regulation D often focus on the initial filing requirements. The most widely known rule is that a Form D must be filed with the Securities and Exchange Commission within 15 days after the first sale of securities. However, compliance obligations do not end once that initial notice is submitted.
Form D filings need to be amended when the company renews the filing for another 12 months, or when there are changes to offering terms, issuer details, or other material information. If these updates are not made in a timely manner, issuers risk regulatory scrutiny and potential compliance deficiencies.
Understanding when a Form D amendment is required is essential for maintaining compliance throughout the life of a private securities offering.
The key concept is that changes must be evaluated cumulatively. If multiple smaller adjustments together exceed the ten percent threshold compared with the last filed notice, an amendment must be filed.
This rule is one of the most misunderstood aspects of Form D compliance. Companies often assume that each small change is irrelevant, without realizing that the combined impact may trigger an amendment requirement.
What Is a Form D Amendment?
A Form D amendment is an updated version of a previously filed Form D notice. Companies preparing their initial filing or amendment often review the SEC’s Form D instructions to understand the required information and how to submit the notice through the EDGAR system. The amendment is filed electronically through the SEC’s EDGAR system and must clearly indicate that it is an amendment to an earlier filing rather than a new notice. Form D amendments serve several purposes. They allow issuers to correct errors in the original filing, update information that has changed since the initial submission, and confirm that an ongoing offering continues to comply with Regulation D reporting expectations. Because Form D filings are publicly available through EDGAR, amendments ensure that regulators and investors have access to current and accurate information about an offering.When Is a Form D Amendment Required?
Amendments are required when certain changes occur after the initial filing. These triggers generally fall into three categories. Understanding these categories helps issuers determine when a previously filed Form D must be updated to remain compliant. The most common amendment triggers include:- Correcting material mistakes or errors discovered in a previously filed Form D notice
- Updating material changes to information disclosed in the original filing, such as changes in issuer details or offering terms
- Filing an annual amendment when an offering continues beyond the one-year anniversary of the most recent Form D filing
Correcting Material Mistakes or Errors
One of the most straightforward triggers for a Form D amendment occurs when the original filing contains an error. If an issuer discovers a material mistake in the previously filed notice, the rules require that an amendment be filed as soon as practicable after the error is discovered. This ensures that the public record accurately reflects the details of the offering. Errors can occur for many reasons. Information may have been entered incorrectly during the EDGAR submission process, or details may have changed shortly after the initial filing. Typical examples include incorrect issuer information, inaccurate offering amounts, or mistakes related to related persons such as directors or executive officers. Therefore, it’s critical to file the updated amendment promptly—it isn’t optional. Partnering with an experienced EDGAR filing agent to manage the process, catch issues early, and reduce the risk of errors is essential.Changes to Information Previously Disclosed
Another major trigger for amendments occurs when key information in the original Form D changes during the offering. Private placements often evolve over time. New executives may join the company, offering structures may change, or compensation arrangements for promoters or placement agents may be adjusted. When these changes affect information that was previously disclosed in the Form D, the issuer must file an amendment reflecting the updated details. Examples of changes that typically require an amendment include:- Addition of executive officers, directors, or promoters
- Changes to the exemption being relied upon
- Changes in the issuer’s identity or organizational structure
- Address/contact information for the company is updated
- Increases in compensation to related parties beyond certain thresholds
The 10 Percent Threshold Rule
Form D rules recognize that offerings often change slightly as capital raises progress. To avoid unnecessary amendments for minor adjustments, the SEC established a threshold rule for certain financial changes. In many situations, changes within a ten percent range do not require an amendment. However, once a change exceeds that threshold, an amendment becomes mandatory. The following table illustrates how the threshold typically applies to common Form D disclosures.| Disclosure Item (Form D) | Change Within 10% | Change Exceeding 10% |
| Item 13 — Total offering amount (Offering and Sales Amounts) | Amendment not required (based on the 10% test) | Amendment required |
| Item 16 — Total sales commissions / total finders’ fees (Sales Compensation) | Amendment not required (based on the 10% test) | Amendment required |
Annual Amendments for Continuing Offerings
Another important trigger for amendments relates to the duration of the offering. Many issuers refer to these required annual updates as Form D renewals because they confirm that an offering reported in a previous Form D filing remains active. If a private offering continues beyond one year after the original Form D filing, the issuer must submit an annual amendment. This update confirms that the offering remains active and provides an updated snapshot of the offering’s status. The annual amendment must be filed on or before the 12-month mark of the most recent Form D filing or amendment. If the offering is still ongoing at that time, the filing is mandatory even if no other changes have occurred. This requirement is particularly relevant for private investment funds, venture capital raises, and other offerings that remain open for extended periods. An ongoing offering requires periodic confirmation through annual Form D amendments.Changes That Do Not Require an Amendment
While certain events trigger amendment requirements, not every change to an offering requires updating the filing. The SEC allows issuers flexibility for minor changes that do not materially alter the disclosure record. Common changes that generally do not require a Form D amendment include:- Changes in the total number of investors
- Updates to the amount of securities sold or remaining to be sold
- Adjustments to issuer revenue or asset value
- Address changes for related persons
- Small changes to offering amounts within the 10 percent threshold
Timing Considerations for Filing Amendments
Timing is a critical element of Form D amendment compliance. Unlike the initial filing rule, which establishes a clear 15-day deadline after the first sale, amendment timing is typically based on the concept of filing as soon as practicable. This standard means that once an issuer becomes aware of a triggering event, the amendment should be prepared and submitted promptly. Waiting too long after discovering an error or material change can create compliance issues. The EDGAR system also imposes technical limitations. Filers can utilize Blue Sky Comply for these amendments.State-Level Implications of Form D Amendments
Although the Form D is a federal notice filing, its implications extend to state-level securities regulation as well. Do States require Amendment Filings? Yes, when a Form D amendment is filed with the SEC, corresponding amendment filings with the states must be filed. State regulators may request amended filings, updated fees, or additional documentation reflecting the change. Because each state maintains its own rules, issuers must review state requirements carefully when submitting amendments. Failing to update state filings can create compliance gaps even if the federal amendment is properly filed.Common Mistakes That Trigger Amendment Issues
Despite the clarity of the amendment rules, many issuers encounter compliance problems due to simple administrative oversights. These issues often arise when companies fail to monitor how changes to an offering affect previously filed disclosures. Some of the most common mistakes include:- Forgetting the annual amendment requirement when an offering continues beyond the one-year anniversary of the most recent Form D filing
- Adding executive officers, directors, or promoters without updating the Form D to reflect the change in related persons
- Failing to track cumulative increases in the offering amount that exceed the ten percent threshold and trigger an amendment
- Assuming no amendment is required simply because no new investors have joined the offering
- Lack of internal monitoring systems to track changes in offering terms, management, or compensation structures
Best Practices for Managing Form D Amendment Triggers
Because private placements often evolve over time, managing amendment triggers requires an organized compliance process. Companies that treat Form D filings as a one-time task often miss important updates later in the offering. A structured approach usually includes several elements:- Monitoring offering changes throughout the capital raise
- Maintaining a compliance calendar that tracks annual amendment deadlines
- Reviewing compensation arrangements and offering amounts regularly
- Assigning responsibility for regulatory filings to an external filing provider.
Conclusion: Staying Ahead of Form D Amendments
Form D amendments are an essential part of Regulation D compliance. They ensure that the SEC and state regulators have accurate information about private securities offerings as they evolve. While the initial filing requirement is widely understood, amendment triggers are often overlooked even more. Material corrections, changes in offering details, and annual updates can all require additional filings. The most effective compliance strategy is proactive monitoring. By tracking offering developments carefully and updating filings when required, issuers can maintain transparency with regulators and avoid unnecessary compliance issues.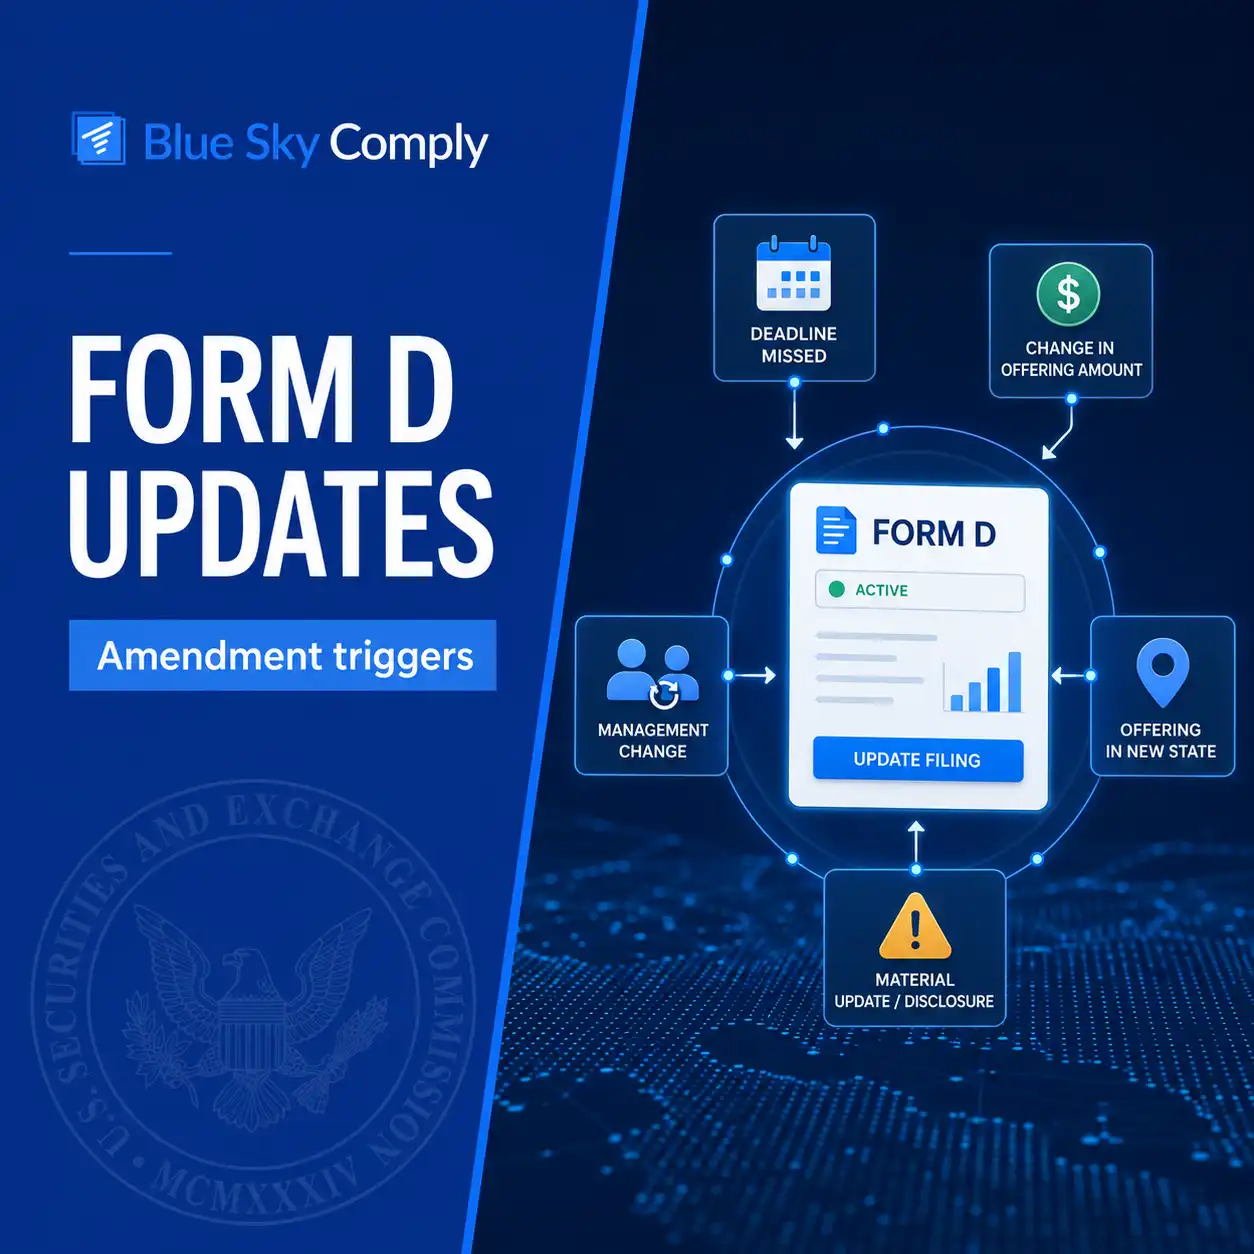
Raising capital under Regulation D or another federal exemption often feels straightforward once the SEC filing is complete. But many issuers learn the hard way that state compliance is where small procedural errors turn into formal notices from regulators. A Blue Sky deficiency letter can interrupt your offering, create unnecessary legal expense, and raise avoidable questions about your compliance controls.
Most deficiency letters are not issued due to fraud. They are triggered by preventable mistakes. Understanding the patterns behind these errors is the first step toward avoiding them.
The difference between smooth compliance and regulatory correspondence is often just a few days.
What Is a Blue Sky Deficiency Letter?
A Blue Sky deficiency letter is a formal communication from a state securities regulator identifying a problem with your notice filing, timing, documentation, or compliance posture. It is typically issued when a regulator believes your filing is incomplete, late, inaccurate, or inconsistent with state requirements. In many cases, the regulator will request corrective action within a defined timeframe. In more serious cases, the deficiency may escalate into late fees, administrative penalties, or even a temporary suspension of offering activity in that state. A deficiency letter is a warning sign. It is not yet enforcement, but it signals regulatory attention. Responding quickly and accurately matters, which Blue Sky Comply can help with. But preventing the letter altogether is far better.Mistake #1: Assuming Federal Exemption Eliminates State Obligations
One of the most common triggers of deficiency letters is the assumption that a federal exemption solves everything. Issuers often rely on Rule 506 under Regulation D and believe that because the offering is federally exempt from registration, no additional state action is required. While Rule 506 offerings are considered covered securities and are preempted from state registration, they are not exempt from state notice filing requirements. States still require:- A copy of Form D
- Payment of the required state filing fee
- Consent to service of process
Mistake #2: Missing the 15 Day Filing Deadline
Timing is one of the most frequent causes of deficiencies. Most states require that a Blue Sky notice filing be made either before the first sale in the state or within 15 calendar days after the first sale. The problem arises when companies accept investor funds and only later confirm which states require filing. Once the 15-day window has passed, the filing is considered late even if it is eventually submitted. Late filings can trigger:- Monetary late fees
- Administrative penalties
- Unregistered sale designation and penalty
- Formal deficiency notices
| Scenario | Filing Timing | Regulatory Outcome |
| Notice filed before first sale | Pre-filing compliance | No deficiency |
| Notice filed within 15 days | Timely compliance | No deficiency |
| Notice filed after 15 days | Late filing | Deficiency letter likely and possibly late fees |
| No filing submitted | Ongoing violation | Enforcement risk |
Mistake #3: Accepting Investors From States Where No Filing Exists
Blue Sky obligations are triggered by the investor's residency, not the issuer's location. An issuer may be headquartered in Texas, but if an investor resides in California, New York, or Illinois, a filing is required in that investor’s state. Online capital raises make this even more complex because investors can participate from anywhere. A common error occurs when:- An investor commits funds from a state where no notice has been filed
- The company processes the investment before completing the state filing
- The filing is rushed after the fact
Mistake #4: Incomplete or Incorrect State Filings
Not all deficiencies are about timing. Many involve documentation errors. State filings often require more than simply uploading Form D. Common administrative mistakes include:- Incorrect fee amount
- Missing correct state-specific forms
- Incorrectly completed filings and forms
- Filing in the wrong system
- Omitting other requirements
Mistake #5: Improper General Solicitation in Rule 506(b) Offerings
Marketing conduct can also trigger Blue Sky scrutiny. Rule 506(b) prohibits general solicitation and advertising. While this is a federal rule, states also enforce anti-fraud and solicitation restrictions under their Blue Sky statutes. Examples that create problems include:- Public social media posts promoting the offering
- Open demo day presentations
- Broad email campaigns without pre-existing relationships
Mistake #6: Failing to File Amendments or Annual Renewals
Compliance does not end after the initial filing. Certain states require annual renewal filings if the offering remains open for more than 12 months. Others require amendments if there are material changes to the offering. Detailed guidance on what constitutes a material change and when updates are required can be found in our Form D Amendment Triggers Explained guide. Issuers sometimes forget that these events automatically trigger updated filings at both the SEC and state level. A regulator who notices outdated information may issue a deficiency letter requesting correction. Ongoing compliance requires structured calendar management, not just initial submission.The True Cost of a Deficiency Letter
While a deficiency letter may seem procedural, the consequences can extend beyond administrative correction. Potential impacts include:- Late fees that range from hundreds to thousands of dollars
- Legal fees for response and remediation
- Enforcement action, including prior offering rescission in the state, a temporary ban from doing offerings in the state, and civil legal judgments
- Reputational concerns with future regulators
How to Prevent Blue Sky Filing Deficiencies
Preventing deficiency letters requires a structured approach. While each offering differs, effective compliance programs typically include the following elements:- Conducting a state-by-state analysis before launch
- Identifying potential investor states during marketing planning
- Filing proactively where marketing is expected
- Implementing investor residency screening during onboarding
- Maintaining a centralized compliance calendar
- Monitoring amendment triggers
Building a Sustainable Blue Sky Compliance Framework
Blue Sky compliance becomes more complex as offerings expand across multiple states. What begins as a single Form D filing quickly turns into multiple state filings. A sustainable compliance framework includes:- Clear assignment of responsibility within the organization
- Standardized documentation processes
- Regular internal compliance reviews
- Coordination between legal, finance, and investor relations teams
Precision Prevents Problems
State regulators are not looking for perfection, but they do expect precision. Most Blue Sky deficiency letters stem from inadequate legal support. Blue Sky Comply’s team of experts works with state regulators on a regular-basis and knows each of them well, which helps prevent such compliance issues discussed in this article. By tracking investor sales carefully and maintaining proper compliance, issuers can avoid unnecessary regulatory scrutiny.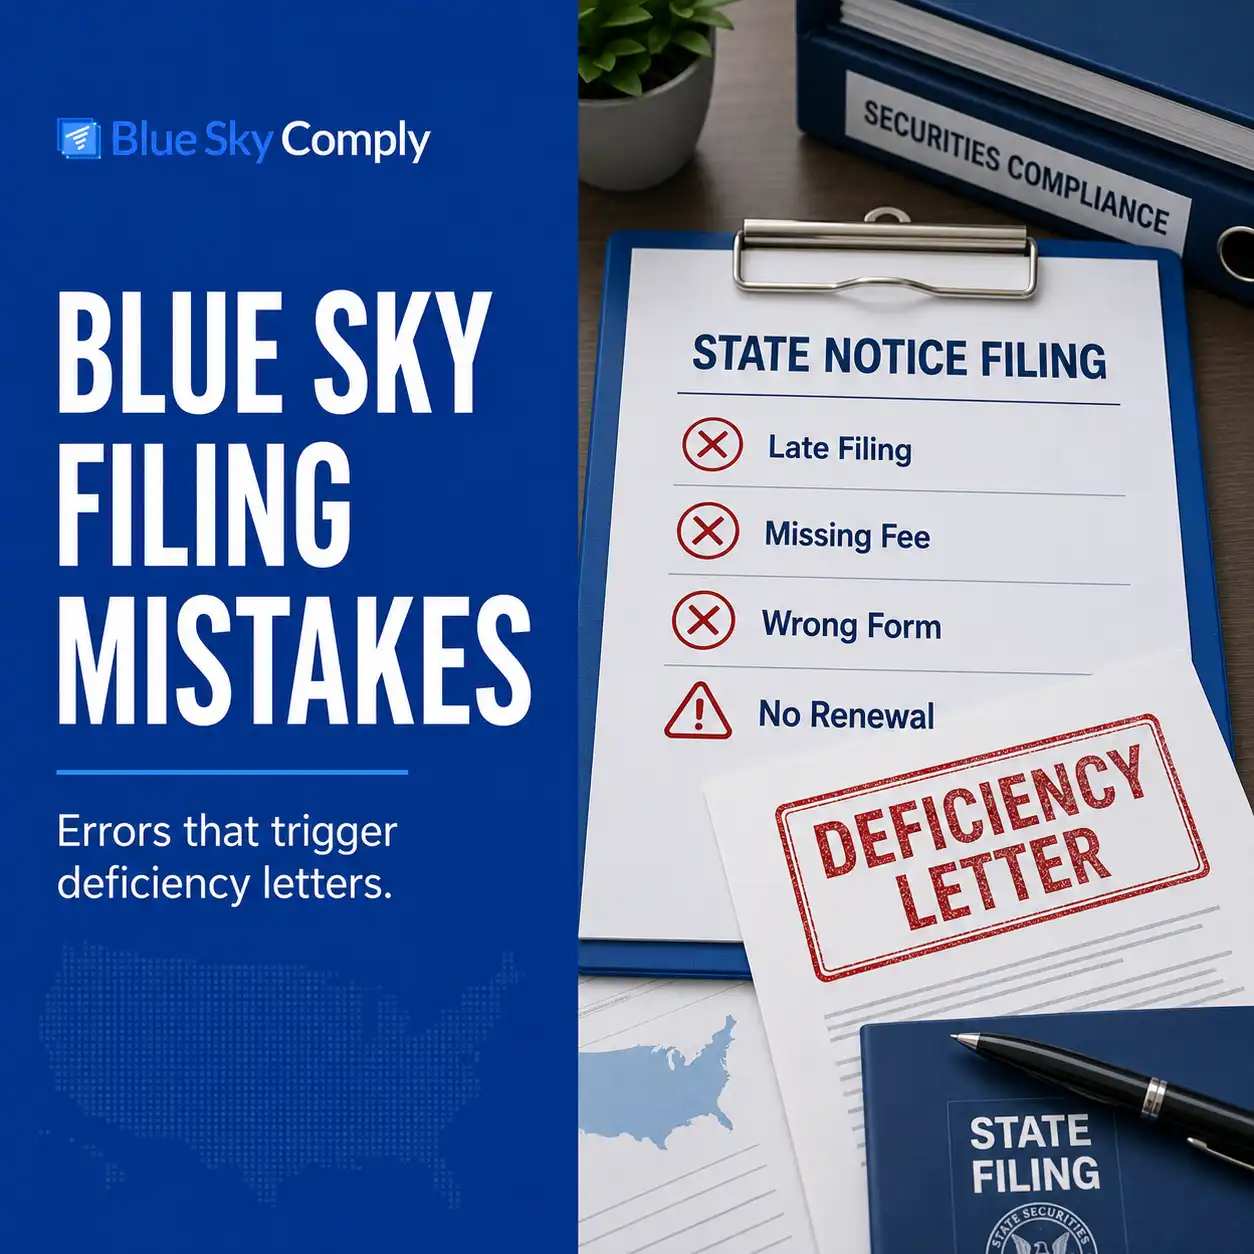
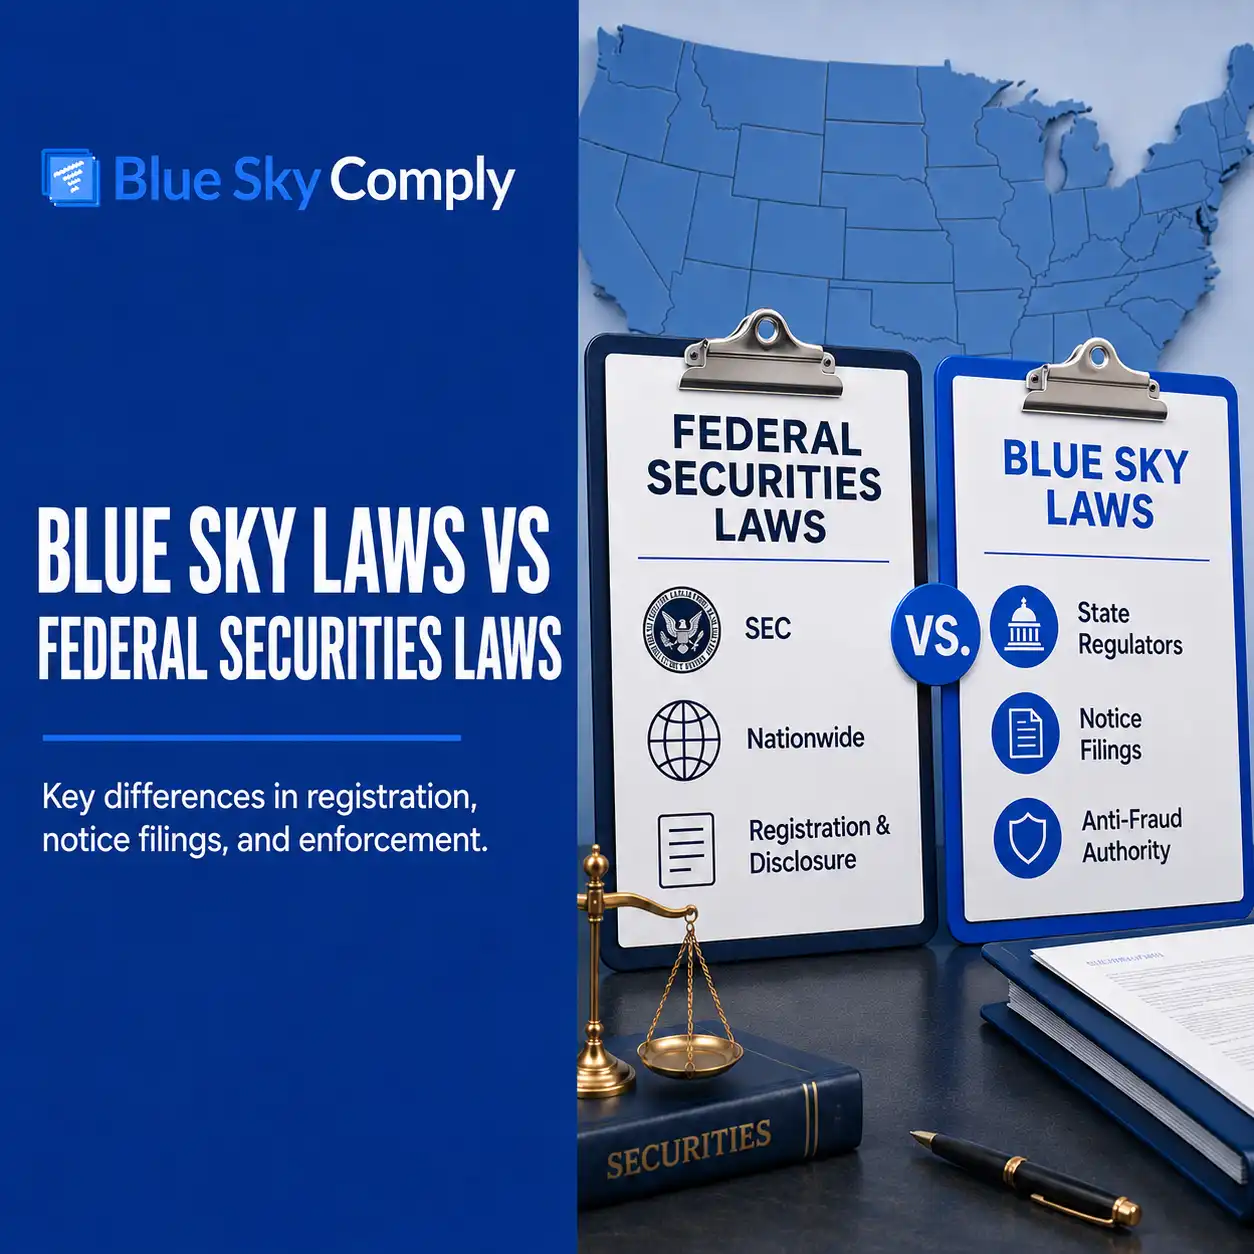
When companies raise capital in the United States, they must navigate two overlapping but distinct regulatory systems: federal securities law and state securities law, commonly known as Blue Sky laws. While these systems are designed to work together, they operate at different levels of government and impose different types of obligations.
Understanding how Blue Sky laws differ from federal securities law is essential for issuers, fund managers, and compliance professionals. Federal exemptions do not automatically eliminate state responsibilities, and state authority does not override federal law. The relationship is layered, not either-or.
This comparison highlights an important principle. Federal law may determine whether a registration statement is required, but state law may still impose additional compliance obligations.
What Is the Difference Between Blue Sky Laws and Federal Securities Law?
At the highest level, the difference is structural. Federal securities laws are enacted by Congress and enforced by the Securities and Exchange Commission. They apply nationwide and govern how securities are offered, sold, and traded. Blue Sky laws are state-level securities laws enforced by individual state regulators. Each state has its own statutes and administrative rules that regulate securities offerings within its borders. Federal law can preempt certain state requirements, particularly registration requirements for covered securities. However, states retain authority to require notice filings and enforce anti-fraud provisions. As a result, issuers often must comply with both systems simultaneously.What Are Federal Securities Laws?
Federal securities laws form the foundation of U.S. capital markets regulation. The two most significant statutes are the Securities Act of 1933 and the Securities Exchange Act of 1934. The Securities Act of 1933 governs the offer and sale of securities. It generally requires that securities be registered with the SEC unless an exemption applies. Registration typically involves filing detailed disclosure documents such as Form S-1 or Form 1-A. The Securities Exchange Act of 1934 regulates secondary trading markets, ongoing reporting requirements, and broker-dealers. It established the SEC and provided the framework for enforcement and disclosure obligations. Federal law also provides exemptions from registration, including:- Regulation D for private placements
- Regulation A for limited public offerings
- Regulation CF for smaller online offerings
- Section 4(a)(2) for transactions not involving a public offering
- Rule 701 for employee compensation and equity incentive plans
- Rule 144A for resales of securities to qualified institutional buyers (QIBs)
- Intrastate offering exemptions (Rule 147 and Rule 147A) for offerings limited to a single state
- Regulation S for offerings conducted outside the United States
What Are Blue Sky Laws?
Blue Sky laws are the securities statutes enacted and enforced by individual states. Although many states base their laws on versions of the Uniform Securities Act, each state has its own regulatory agency and administrative rules. Blue Sky laws typically regulate:- Registration or qualification of securities offerings
- Licensing of brokers and investment advisers
- Anti-fraud provisions related to securities transactions
Registration Requirements: Federal vs State
The most significant distinction between federal and state securities law lies in registration requirements. At the federal level, securities must be registered with the SEC unless an exemption applies. Registration involves detailed disclosures about the issuer’s business, financial condition, risk factors, and management. The SEC reviews the filing for compliance with disclosure standards. At the state level, registration requirements historically required issuers to qualify their offerings in each state where securities were sold. However, federal legislation has significantly altered this landscape. To clarify the structural differences, the table below compares federal and state securities law in key areas:| Requirements | Federal Securities Laws |
Blue Sky State Laws |
| Primary Regulator | Securities and Exchange Commission | State securities regulators |
| Geographic Scope | Nationwide | Individual states |
| Registration Requirement | Required unless exempt | Required unless preempted or exempt |
| Review Standard | Disclosure-based | May include merit review in some contexts |
| Anti-Fraud Authority | Yes | Yes |
| Notice Filings | Not applicable | Often required for covered securities |
Federal Preemption and Covered Securities
The relationship between federal and state securities law changed significantly in 1996 with the passage of the National Securities Markets Improvement Act. This legislation created the concept of “covered securities.” Covered securities are exempt from state registration requirements. They include securities sold under Rule 506 of Regulation D and securities listed on national exchanges. This means that if an issuer conducts a Rule 506 offering, states cannot require full registration or merit review of that offering. However, preemption does not eliminate all state authority. States may still:- Require state notice filings with state-specific filing requirements that vary
- Collect filing fees based on the offering amount, and other factors found in the offering
- Enforce anti-fraud provisions
Notice Filings Versus State Registration
One of the most common sources of confusion is the difference between state registration and a Blue Sky notice filing. State registration is a substantive process. It may involve reviewing offering documents, financial disclosures, and, in some cases, evaluating whether the offering is fair to investors. A notice filing, by contrast, is less burdensome but typically requires submitting a copy of Form D and other state-specific forms and documents, paying a state-defined blue-sky fee, and providing consent to service of process. The state does not conduct a merit review but is formally notified of the offering. Notice filings are most commonly required for Rule 506 offerings under Regulation D. Issuers must file in each state where investors reside, usually within a specified time after the first sale.Enforcement Authority: SEC vs State Regulators
Federal and state regulators both have enforcement authority, and in some cases, their jurisdictions overlap. The SEC may bring civil enforcement actions for violations of federal securities laws, including misstatements, omissions, and fraudulent conduct. Remedies may include injunctions, penalties, and disgorgement. State regulators may also bring enforcement actions under their own Blue Sky laws. Even when an offering is federally exempt and preempted from state registration, states retain the power to investigate and prosecute fraud within their jurisdiction. In practice, federal and state enforcement actions can occur independently or in parallel. Compliance strategies must account for both levels of oversight.When Must Issuers Comply With Both Systems?
In most capital raises, issuers must comply with both federal and state securities laws simultaneously. For example, a company conducting a Rule 506 offering must:- Comply with Regulation D at the federal level
- File Form D with the SEC
- Submit Blue Sky notice filings in each state where investors reside
Common Misunderstandings About Federal and State Law
Several misconceptions arise not from filing mechanics, but from confusion about how regulatory authority is divided between federal and state governments. “Federal law is superior, so it replaces state law.” Federal securities law can preempt specific state requirements, particularly those related to the registration of covered securities. However, preemption is limited and defined by statute. States retain independent authority to enforce anti-fraud provisions and, in many cases, require notice filings and fees. Federal law does not eliminate state securities law. “State regulators simply enforce federal rules.” State securities divisions operate under their own statutes and administrative frameworks. While many state laws are modeled on versions of the Uniform Securities Act, they are not merely extensions of the SEC. States can initiate investigations, issue stop orders, and pursue enforcement actions independently of federal authorities. “If an offering is small, state law does not apply.” The size of the offering does not determine whether state securities law applies. State jurisdiction is generally triggered by the offer or sale of securities to residents within the state, regardless of offering size. “Blue Sky laws are outdated and rarely enforced.” Although federal regulation has expanded over time, state regulators remain active participants in securities oversight. States regularly bring enforcement actions, coordinate with the SEC, and monitor notice filings to ensure compliance. Understanding these structural distinctions helps issuers recognize that federal and state law operate concurrently rather than in a hierarchical manner. Compliance requires satisfying both systems where applicable.Why the Difference Matters
Understanding how Blue Sky laws differ from federal securities law is not merely academic. It directly impacts how offerings are structured, filed, and managed. Issuers who focus solely on federal exemptions risk overlooking state-level notice requirements. Conversely, misunderstanding federal preemption may lead to unnecessary state registration efforts. A coordinated compliance approach recognizes that:- Federal law establishes nationwide disclosure and exemption frameworks
- State law supplements federal oversight through notice filings and enforcement
- Both systems must be satisfied to lawfully offer securities
Raising capital in the United States often involves navigating both federal and state securities laws. Many issuers focus on federal exemptions such as Regulation D or Regulation A, only to discover that state-level requirements still apply. One of the most common of these state obligations is the Blue Sky notice filing.
Although it is generally more streamlined than full state registration, a Blue Sky notice filing is not optional. It plays a critical role in ensuring compliance with state securities regulators and protecting investors from fraud. Understanding what it is, when it is required, and how it works is essential for any issuer conducting a securities offering.
What Is a Blue Sky Notice Filing?
A Blue Sky notice filing is a state-level securities filing required when an issuer relies on certain federal exemptions from registration. While federal law may preempt full state registration, states often retain the authority to require a notice filing, payment of a filing fee, and submission of specified documents. In practical terms, a Blue Sky notice filing typically involves submitting a copy of Form D, paying a state fee, and providing additional state-specific information and documents. The filing signifies to state regulators that securities are being offered to residents of their state under a federally exempt offering. Even when an offering is exempt from federal registration, it may still require state notice filings.What Are Blue Sky Laws?
Blue Sky laws are state securities laws designed to protect investors against fraudulent sales practices and deceptive offerings. Every state has its own securities statutes, regulatory agency, and enforcement authority. The term “blue sky” dates back to early 20th-century efforts to curb speculative schemes that had little substance behind them. These laws aim to prevent the sale of securities backed by nothing more than “blue sky.” Although the Securities Act of 1933 and subsequent federal legislation established national standards, state laws were never eliminated. Instead, they operate alongside federal regulations. In many cases, federal law preempts state registration requirements, but states retain anti-fraud authority and the ability to require notice filings. Blue Sky laws generally regulate:- The registration of securities offerings
- The licensing of brokers and investment advisers
- Anti-fraud provisions related to securities sales
Why Is a Blue Sky Notice Filing Required?
To understand why notice filings exist, it helps to distinguish between state registration and federal preemption. In 1996, Congress enacted the National Securities Markets Improvement Act, which created the concept of “covered securities.” Covered securities, including those sold under Rule 506 of Regulation D, are exempt from substantive state registration requirements. This means states cannot require a full merit review or registration process for these offerings. However, federal preemption does not eliminate all state authority. States may still:- Enforce anti-fraud provisions
- Require notice filings
- Collect filing fees
When Is a Blue Sky Notice Filing Required?
Blue Sky notice filing requirements depend on the type of offering and where investors are located.Regulation D Offerings
Most private offerings are conducted under Rule 506(b) or Rule 506(c) of Regulation D. These offerings qualify as covered securities and are exempt from state registration. However, issuers must still make notice filings in each state where a purchaser resides. In many states, the notice filing must be made within 15 days after the first sale of securities in that state. Some states require filings before the first sale. Timing varies by jurisdiction.Regulation A Offerings
Regulation A offerings are divided into two tiers. Tier 1 offerings generally require compliance with state registration requirements, which means issuers may need to qualify their offerings at the state level. Tier 2 offerings benefit from federal preemption of state registration. However, almost all states still require notice filings or fees.Regulation Crowdfunding
Regulation Crowdfunding offerings are also generally preempted from state registration. Nevertheless, the state anti-fraud authority remains intact, and notice and state filing fee obligations may apply in limited circumstances. The key factor is investor location. If you sell securities to residents of multiple states, you may trigger notice filing requirements in each of those states.What Information Is Included in a Blue Sky Notice Filing?
Although requirements vary, most Blue Sky notice filings are relatively straightforward. A typical notice filing may include:- A copy of Form D filed with the SEC
- A consent to service of process
- State-specific filing forms
- Payment of the required filing fee
The Regulatory Function and Consequences of Blue Sky Non-Compliance
While the National Securities Markets Improvement Act of 1996 (NSMIA) preempts states from reviewing the merits of Rule 506 Regulation D offerings, it explicitly preserves state authority to require notice filings and collect fees. These filings are not administrative suggestions; they are the mechanism by which an issuer perfects its federal preemption at the state level. Failure to timely file a Blue Sky notice jeopardizes the issuer’s exemption and exposes the company to three distinct categories of risk:Statutory Rescission Rights (Civil Liability)
The most significant material risk of a missed filing is the possibility of specific performance in the form of rescission. If a filing is missed, the sale may be legally categorized as an unregistered securities transaction. This grants investors a statutory "put option"—the right to demand the return of their principal investment plus statutory interest and attorney fees. This potential liability remains on the balance sheet regardless of the company’s financial health.State Enforcement and Administrative Penalties
State securities divisions retain jurisdiction to enforce compliance. Regulators typically respond to failures to file with a graduated scale of enforcement actions, including:- Monetary Penalties: Assessment of retroactive late fees and civil fines.
- Stop Orders: Summary suspension of the offering within that jurisdiction.
- Consent Orders: Public settlement agreements that may label the issuer or its officers as "bad actors," effectively disqualifying them from utilizing Rule 506 safe harbors in future capital raises.
Impediments to Future Financing and Exits
Non-compliance creates a strict liability defect in the company’s capitalization. Institutional investors and acquirers routinely conduct diligence on Blue Sky compliance manifests. A pattern of missed filings serves as a diligence "red flag," often compelling the issuer to undertake costly "clean-up" filings and typically delaying the closing of subsequent financing rounds or exits. For an analysis of the correlation between filing deficiencies and federal regulatory scrutiny, including specific instances where Form D errors have triggered SEC enforcement actions, please refer to Compliance Failures: Form D and Blue Sky Filings.Common Misunderstandings About Blue Sky Notice Filings
There are several persistent misconceptions surrounding Blue Sky notice requirements. Clarifying these misunderstandings can prevent avoidable compliance and regulatory issues.- “Filing Form D with the SEC satisfies all requirements.” Filing Form D is only the federal component of the compliance process. State Blue Sky notice filings are separate obligations and must be made individually in each state where investors reside.
- “Federal preemption eliminates all state involvement.” While federal law may preempt state registration requirements for covered securities, states retain authority to enforce anti-fraud laws and to require notice filings and the submission of state fees.
- “Only the issuer’s home state matters.” Blue Sky notice obligations are triggered by investors' residency, not the issuer's location. If securities are sold to investors in multiple states, filings may be required in each jurisdiction.
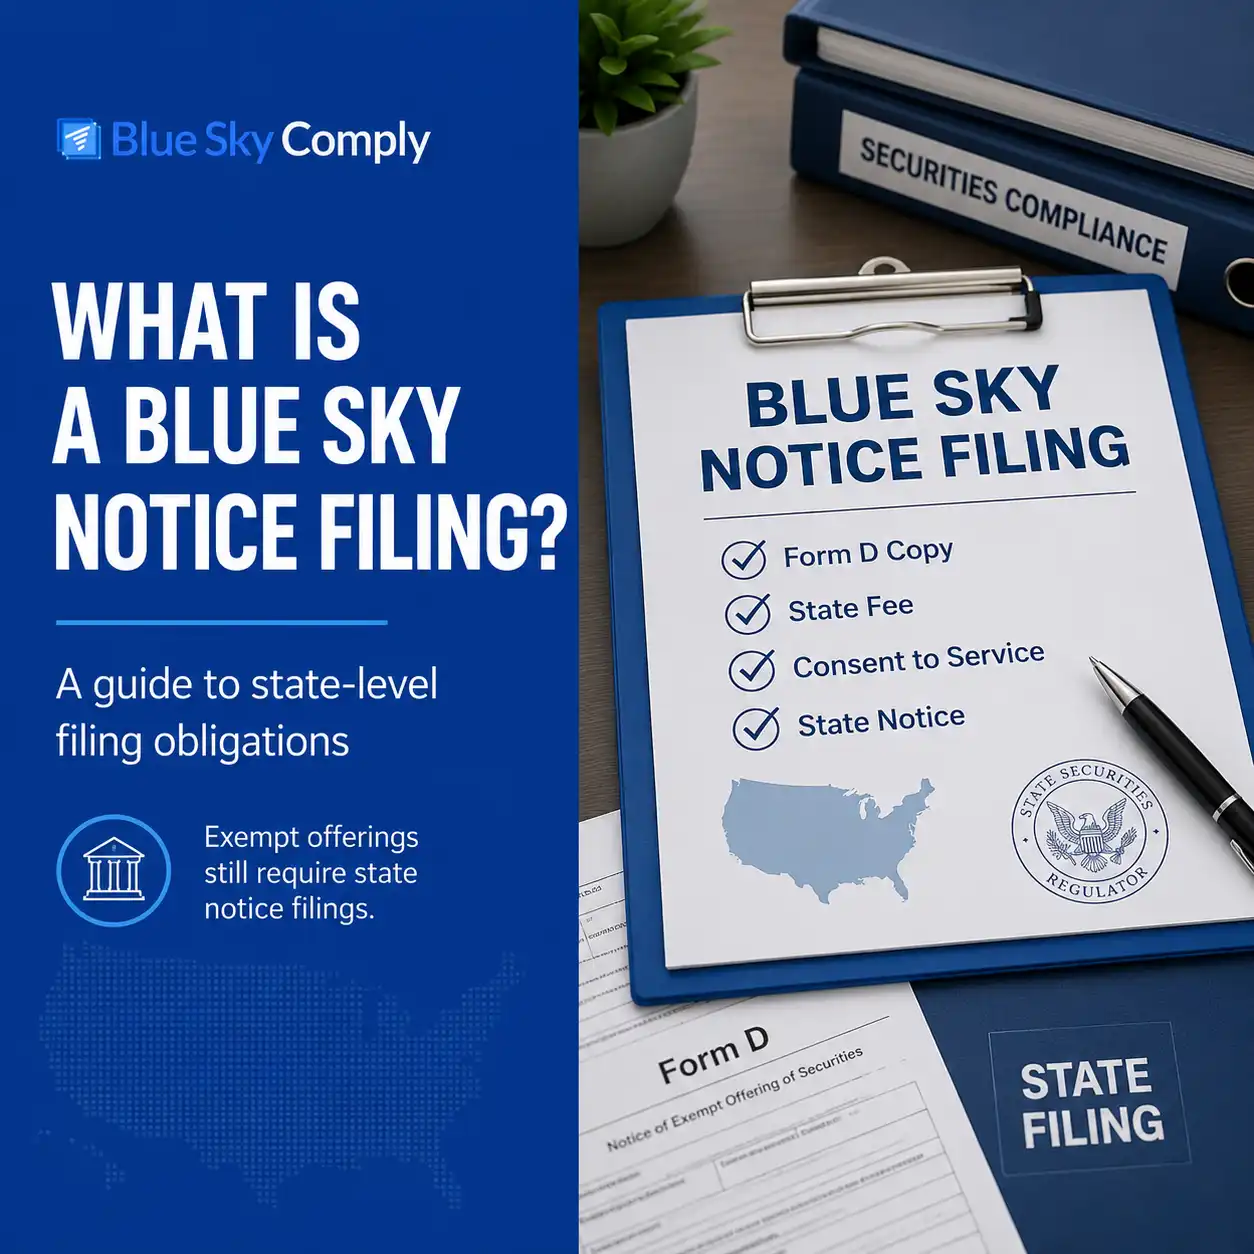
Yes, Rule 504 permits advertising, but only if the offering is structured to meet specific conditions tied directly to state securities regulations. In other words, Rule 504 is not a blanket permission to market a private raise publicly. Rule 504 is a limited federal exemption with a practical reality: your ability to advertise often depends on how you comply with state Blue Sky laws.
Many founders and issuers ask this question because marketing is how most modern fundraising happens. A LinkedIn post, a pitch page, a targeted ad, or a simple “we are raising” email can quickly become public-facing. Under many private offering exemptions, such outreach can create immediate compliance issues. Rule 504 is unusual because, in certain cases, it can accommodate broader marketing, but only if the rest of the compliance structure supports it.
Rule 504 is within Regulation D, which generally imposes restrictions on “general solicitation” and “general advertising.” Those restrictions are famously strict under Rule 506(b), less strict under Rule 506(c), and conditional under Rule 504. Understanding those differences is the key to answering the advertising question correctly.
The big takeaway: with Rule 504, advertising is not a standalone choice. It is a consequence of the regulatory pathway you select.
Under Rule 504, marketing and state compliance strategies must be designed together.
What is Rule 504, and when do issuers use it?
Rule 504 is a Regulation D exemption that allows eligible issuers to offer and sell up to $10 million in a 12-month period without registering the offering with the SEC. This offering limit was increased from $5 million to $10 million through SEC amendments effective March 15, 2021. Rule 504 is generally available only to certain non-reporting issuers and excludes certain categories of issuers, such as investment companies. A key point for issuers is that Rule 504 also requires intensive compliance with state securities laws in the states where offers and sales occur. That last point is what makes Rule 504 highly relevant to advertising questions. Unlike Rule 506 offerings, Rule 504 generally does not come with the same broad federal preemption of state registration requirements. As a result, state-level compliance often becomes the gating factor for how the offering can be conducted, including whether and how it can be marketed.What counts as “advertising” or “general solicitation” in Reg D?
In Regulation D, “general solicitation” and “general advertising” are not defined by a single modern checklist, but the rules do provide examples. Rule 502(c) covers communications such as newspaper and magazine advertisements, broadcast media, and public seminars at which attendees were invited through general advertising. In today’s context, issuers usually think about general solicitation more practically: if you are communicating offering information to people you do not have a pre-existing, substantive relationship with, and you do it publicly or broadly, you are likely in solicitation territory. Here are common activities that are typically treated as general solicitation in practice:- Public social media posts announcing the raise or offering terms
- Online ads targeting broad audiences
- Mass email blasts to lists where recipients do not have a prior relationship with the issuer
- Public-facing offering pages that invite anyone to invest
When is advertising permitted in Rule 504 offerings?
Rule 504 does not automatically allow advertising. Instead, the rule limits the circumstances in which general solicitation is permitted. The SEC’s framework is designed to prevent Rule 504 from becoming a backdoor public offering while still allowing certain smaller raises to market more broadly when appropriate investor protections are in place at the state level. In plain terms, advertising under Rule 504 is typically possible when the offering is either:- Registered in at least one state with a substantive review process that includes public filing and delivery of a disclosure document to investors before sale (with delivery to all purchasers), or
- Conducted exclusively under state law exemptions that permit general solicitation and general advertising, but only if sales are made to accredited investors.
| Rule 504 approach | Can you advertise? | What you generally must do to support it |
| State registration pathway | Often yes | Register in at least one state with substantive disclosure requirements; make offers and sales in that state in compliance with the state process; deliver the required disclosure document to all purchasers before sale |
| State exemption pathway that permits solicitation | Sometimes yes | Rely exclusively on state exemptions that allow solicitation; limit sales to accredited investors (where required by the exemption structure) |
| No state structure that supports solicitation | Usually no | Avoid public advertising; shift to a more controlled outreach strategy or consider a different exemption that fits your marketing plan |
How does Rule 504 advertising compare to Rule 506(b) and Rule 506(c)?
Founders often hear that “Reg D means no advertising,” which is only partly true. The rules depend on which exemption you rely on and how you handle investor eligibility. At a high level:- Rule 506(b): general solicitation is not permitted, and issuers generally rely on pre-existing relationships.
- Rule 506(c): general solicitation is permitted, but sales must be to accredited investors, and issuers must take reasonable steps to verify accredited status.
- Rule 504: general solicitation may be permitted only in the limited circumstances described above, often tied to state registration or state exemptions, and it generally does not provide the same state preemption dynamics as Rule 506.
What should issuers do before promoting a Rule 504 raise?
Before you publish a post, run ads, or direct traffic to an offering page, treat the offering as a structured compliance project rather than a marketing campaign. In Rule 504, the most common problems arise when communication moves faster than planning. Here is a short, practical set of steps issuers typically consider before they promote:- Confirm you are eligible for Rule 504 and remain within the $10 million 12-month cap
- Decide whether your plan involves true public marketing or controlled outreach
- Identify where your prospective investors are located, since state obligations follow investor residency
- Choose the pathway that supports advertising (state registration route or state exemption route that permits solicitation)
- Keep offering communications consistent, documented, and aligned with the exemption you are relying on
Final Words
Rule 504 can be a useful exemption for smaller capital raises and may permit advertising in limited circumstances. But the permission to advertise is not the default. It is conditional, and those conditions often connect directly to how the offering is being handled under state Blue Sky laws. If you approach Rule 504 with the mindset that “advertising is allowed,” you risk building the wrong process. If you approach it with the mindset that “advertising must be earned by structure,” you are far more likely to stay within the exemption and avoid surprises later. Blue Sky Comply helps companies coordinate the state Blue Sky requirements that often determine whether and how a Rule 504 offering can be advertised.
Private companies raise capital at many stages of their lifecycle, often long before public markets are an option. In these early and growth phases, registering securities with the SEC is usually impractical due to cost, timing, and disclosure burdens. Section 4(a)(2) of the Securities Act provides a critical path forward by allowing certain private offerings to proceed without registration.
This exemption is not simply a procedural shortcut. It reflects a core principle of U.S. securities law: full registration is not necessary when securities are offered privately to investors who can protect their own interests. For issuers, Section 4(a)(2) offers flexibility. For regulators, it preserves investor protection by imposing expectations around disclosure, sophistication, and offering conduct.
Understanding how Section 4(a)(2) works is essential for issuers that want to raise capital responsibly while avoiding regulatory exposure that may surface later during diligence, audits, or transactions.
*This does not constitute as legal advice. Please consult your legal counsel for specific guidance.
A defining feature of a valid private placement is the absence of general solicitation. Public advertising, open websites, or broadly disseminated investment materials can undermine the private character of the offering, even if only a small number of investors ultimately participate. Regulators look closely at how investors were approached, not just who invested.
Ultimately, Section 4(a)(2) is less about what an issuer calls an offering and more about how the offering is actually executed. Issuers that align investor selection, disclosure practices, and solicitation methods are far better positioned to rely on the exemption with confidence.
Issuers often rely on Regulation D because it reduces uncertainty. However, the underlying legal foundation remains Section 4(a)(2), and failures in execution can still raise questions even when a safe harbor is claimed.
What Is Section 4(a)(2) and When Does It Apply
Section 4(a)(2) exempts from registration “transactions by an issuer not involving any public offering.” Unlike many SEC rules, it does not contain numeric thresholds or rigid eligibility tests. Instead, it is a principles-based exemption that depends on the facts and circumstances of each offering. At its core, Section 4(a)(2) applies when securities are offered privately rather than to the general public. The exemption focuses on the nature of the offering, the relationship between the issuer and investors, and the level of information made available. If an offering resembles a public solicitation in form or substance, it is unlikely to qualify. Because of this flexibility, Section 4(a)(2) has historically served as the legal foundation for private placements. Many later rules, including Regulation D, were designed to provide safe harbors that clarify how issuers can reliably meet the Section 4(a)(2) standard.What Defines a Valid Section 4(a)(2) Private Placement
Section 4(a)(2) does not operate as a bright-line rule. Courts and regulators evaluate whether an offering qualifies by looking at the overall substance of the transaction rather than any single requirement. The focus is on whether the offering is genuinely private in nature and whether investors are able to protect their own interests without the protections of SEC registration. In practice, issuers rely on Section 4(a)(2) when certain core conditions are met around the investors involved, the information they receive, and how the offering is conducted. These elements work together to establish whether the exemption is available. Here is when issuers can rely on Section 4(a)(2) and what is generally expected to support that reliance:| Key Consideration | When Section 4(a)(2) Can Be Used | What Issuers Are Expected to Do |
| Nature of the offering | The offering is private and not available to the general public | Limit participation to a defined group of investors |
| Investor sophistication | Investors are financially sophisticated or advised by professionals | Evaluate investor experience or access to qualified advisors |
| Access to information | Investors can obtain material information about the issuer | Provide meaningful financial and risk information |
| Solicitation methods | No general solicitation or public advertising is used | Avoid mass marketing, public promotions, or broad outreach |
| Issuer-investor relationship | The issuer has a direct or controlled relationship with investors | Maintain disciplined, documented offering communications |
Investor Qualifications and Disclosure Expectations
Although Section 4(a)(2) does not mandate a specific disclosure document, it does impose a practical disclosure obligation. Investors must be given sufficient information to make an informed investment decision. The level of disclosure required depends on who the investors are and how sophisticated they may be. When investors are accredited and financially experienced, disclosure expectations may be less formal but still substantive. When investors are not accredited, issuers face heightened expectations to provide detailed financial and risk information. In all cases, the information must be accurate, complete, and consistent across investors. This is why private placement memoranda are commonly used even when not legally required. They help demonstrate that investors were given access to material information and that the offering was conducted with appropriate care.Section 4(a)(2) Compared to Regulation D
Although Section 4(a)(2) stands on its own, most issuers encounter it in practice through Regulation D. Regulation D does not replace Section 4(a)(2). Instead, it provides safe harbors that define specific conditions under which a private offering is presumed to satisfy the Section 4(a)(2) standard. To put the relationship in context, the table below highlights how these concepts work together:| Exemption Framework | Purpose |
| Section 4(a)(2) | Statutory exemption for private offerings |
| Regulation D | Safe harbor rules that clarify how to comply |
| Rule 506(b) | Traditional private placement without general solicitation |
| Rule 506(c) | Private placement allowing general solicitation with verification |
What Are Common Section 4(a)(2) Compliance Risks
Compliance issues under Section 4(a)(2) rarely stem from a single mistake. More often, they arise from a series of informal practices that, taken together, undermine the private nature of an offering. Issuers may inadvertently engage in general solicitation through online communications, investor referrals, or inconsistent marketing materials. Others fail to maintain adequate records showing what information was provided and when. In some cases, issuers assume that prior offerings establish a precedent, even though each offering must independently satisfy the exemption. Common risk areas include:- Informal or undocumented investor communications
- Uneven disclosure among investors
- Poor coordination between legal, finance, and fundraising teams
How Section 4(a)(2) Interacts With State Blue Sky Laws
Federal exemption under Section 4(a)(2) does not eliminate state securities law considerations. States retain authority under their Blue Sky laws to regulate securities offerings within their jurisdictions, and private placements may still be subject to notice filings or exemption requirements at the state level. The complexity increases as offerings involve investors in multiple states. Each jurisdiction may apply different standards or procedural requirements under its Blue Sky framework. Ignoring these obligations can delay transactions or trigger enforcement actions, even when the federal exemption is otherwise sound. Federal compliance and state compliance under Blue Sky laws are related but distinct responsibilities. Issuers that address both proactively are better positioned to manage regulatory risk as their investor base expands.How Should Companies Manage Section 4(a)(2) as They Grow
As companies raise capital repeatedly, private placements tend to become more frequent, larger in size, and more complex. What worked for an early seed round may not be sufficient for later growth-stage financings. Effective management of Section 4(a)(2) offerings requires discipline. Issuers benefit from consistent documentation, clear internal processes, and a structured approach to investor communications. Treating private placements as formal securities offerings rather than ad hoc transactions reduces risk and improves transparency. Early attention to compliance also pays dividends during diligence. Investors and acquirers scrutinize prior offerings closely, and clean compliance histories reduce friction at critical moments.Final Thoughts
Section 4(a)(2) remains one of the most important exemptions in U.S. securities law. It gives issuers flexibility to raise capital privately while preserving investor protections through disclosure and offering discipline. Its strength lies in its adaptability, but that same flexibility requires careful judgment. Issuers that understand the principles behind Section 4(a)(2), rather than relying on assumptions or informal practices, are better equipped to raise capital responsibly and sustainably. Blue Sky Comply supports issuers in managing the state-level compliance obligations that often accompany private placements under Section 4(a)(2).
Choosing a path for your early capital raise is less about buzzwords and more about fit. Rule 504 sits inside Regulation D and can be a practical option when you want a lighter lift for a smaller offering, especially if your investor base is close to home. The decision often hinges on a few grounded realities:
- Size of the round
- Who your investors are
- How widely you plan to market
- Whether you can embrace state-level steps.
What Rule 504 Is and How It Works
Rule 504 supports smaller offerings with a comparatively simple structure. Broadly speaking, it can allow certain flexibility when the offering is registered at the state level, and it permits sales to both accredited and non-accredited investors, subject to state rules. Documentation and disclosure/filing requirements for Reg D 504 are simple on the federal-filing side to the SEC, but more complicated on the state level. Further, you will spend most of your energy coordinating state requirements, since federal preemption is not the default advantage. Contact us to learn more. State review and registration are what make 504 feel different in practice. Your marketing leeway often flows from what a specific state has reviewed and allowed. If you plan to sell only in a handful of states, you can right-size the process and move faster. If you plan to market broadly across many states, the complexity can add up. Rule 504 could be fast and flexible for small rounds, but varying state requirements will likely determine your true cost and timeline.When Rule 504 Is a Good Fit
Rule 504 tends to click for companies that already have a defined local or regional audience and want to raise a modest amount without building a national marketing campaign. Imagine a consumer brand with loyal customers in two or three states, or a real estate vehicle focused on one metro area. The practical benefits are speed, familiarity with the investor base, and fewer moving parts than a larger retail pathway. If your investors are not all accredited or you have more than 35 non-accredited investors, a state-registered 504 can offer a compliant on-ramp where 506(c) and (b) would not fit your plan. A founder with a strong email list and in-market events might find 504 especially appealing. The existing relationships compress the marketing cycle, and the alignment between your intended investors and the states you choose to register in keeps the filing work proportional to the raise.When Rule 504 Might Not Be the Best Choice
Rule 504 will struggle to keep pace if your strategy looks national, your investor mix is primarily accredited, and you want to openly advertise online. In that scenario, 506(c) can deliver general solicitation with federal preemption on state law, which simplifies the filing posture and helps you move faster across state lines. If your vision is a truly retail-friendly offering at a larger scale with broad reach, Regulation A Tier 2 is often the correct framework, even though it brings ongoing reporting and audited financials. If you expect to run a platform-based, community-centric campaign, Regulation CF may be a better match than 504. The portal infrastructure can be worth the tradeoffs when your goal is to grow your audience from the crowd. If your plan is to market broadly to accredited investors nationwide, 506(c) is usually more efficient than Rule 504.Rule 504 Compared to 506(b) and 506(c)
The differences between these Reg D routes come down to solicitation, investor eligibility, and how much state-level coordination you want. With 506(b), you can avoid general solicitation and raise funds from accredited investors and up to 35 sophisticated non-accredited investors, leveraging preexisting relationships. It is quiet and controlled. With 506(c), you gain the right to generally solicit, but you must verify accreditation status. In both cases, federal preemption lightens the state burden. With Rule 504, you can gain more flexibility via state registration, but the tradeoff is the filing and review workload that sits with those states. If your raise is concentrated where you already do business, that tradeoff can be worth it.Rule 504 vs Regulation CF
Crowdfunding under Reg CF formalizes the public campaign format. You will work through a registered portal, follow disclosure templates, and accept investment caps and limits that come with the territory. The upside is access to a broad retail audience and platform tools designed for conversion. You can raise from unlimited non-accredited investors up to $5mm. By contrast, Rule 504 is most compelling if you can focus on a few states, tailor your messaging to what those states have reviewed, and lean on existing customer affinity. If your plan already involves a portal and national outreach, you will likely be better served by Regulation CF.Rule 504 vs Regulation A Tier 2
Reg A Tier 2 is the heavyweight retail exemption suitable for larger raises with a wide audience, which allows non-accredited investors and free-trading shares suitable for trading. It introduces audited financials, offering circular review and ongoing reporting, all of which support a durable investor relations posture. That structure brings credibility and reach, but it also brings time and budget commitments. Rule 504 is the smaller, faster option for local raises where the goal is to get to a close efficiently without building the infrastructure of a national retail offering. If your strategy anticipates scaling marketing and investor count significantly, a Reg A Offering deserves a serious look.Can You Advertise a Rule 504 Offering?
The short answer is yes, but only under specific conditions tied to state law. Rule 504 by itself does not grant a blanket right to advertise. Public solicitation is permitted when your offering is registered in the states where you intend to solicit or when you use a state exemption that expressly allows general solicitation and requires a public filing and delivery of a disclosure document. In these situations, your ads and public statements should be consistent with what the state reviewed and permitted. If you are not pursuing a path that allows general solicitation under state law, treat communications like a traditional private placement and avoid public promotion. Many issuers that want broad public outreach choose 506(c) instead, because it permits general solicitation with federal preemption. When in doubt, align your plan with state-reviewed materials and keep copies of everything you publish.State Compliance Realities Under Rule 504
The mechanics of 504 are won or lost in the details of state coordination. Each state may have its own form of review (merit-based or disclosure-based reviews), comment cycles, and timelines. Fees also vary. Because your marketing claims should match the filed terms that a state has approved, you will want your marketing and legal teams to communicate closely. For issuers working across a handful of states, it can help to sequence filings based on expected investor demand and processing speed. Select the states where your investor list is strongest, start there, and avoid overextending your filing footprint until you see conversion. When you need a reference point for what these filings entail, it is useful to look at the broader category of State Reg D filings so you can budget time and resources. The core idea is the same:- Plan for state and legal fees
- Filing documents and paperwork
- Examiner comments
- Align your calendar accordingly
Costs, Timelines, and Documentation
Issuers sometimes underestimate the time and attention required to align marketing with state-reviewed materials. A realistic plan includes a calendar for filing and comment resolution in each state, time for drafting and revising offering documents, and a playbook for what your team can and cannot say during the campaign. It also includes recordkeeping and post-close filings, particularly if you accept investments in tranches. To avoid surprises, map your budget to state fees and core drafting tasks. Documentation usually includes subscription agreements, investor questionnaires, disclosure materials that mirror state filings, and carefully reviewed communication materials. Here is a simple view that helps set expectations without drowning in details:| Topic | What to expect under Rule 504 | Practical tip |
| State reviews | Vary by state, with possible comment cycles | Sequence filings by expected demand and speed |
| Fees | Vary by state and can compound across jurisdictions | Build a per-state fee model and track actuals |
| Marketing | Tied to what has been filed or approved | Keep marketing aligned with filed terms and disclosures |
| Investor mix | Can include non-accredited investors with state registration | Pre-plan investor communications and FAQs |
| Timeline | Often faster for a few states, longer for many | Pilot in core states before expanding |
Marketing and Communications Under Rule 504
Good messaging respects what you have filed. If a state has reviewed and cleared specific claims, lean on that approved language. Do not improvise on terms, and do not make performance promises. Your investor communications should be templated, and your team should know which materials are greenlit and which need legal review before use. A well-run 504 campaign often looks and feels like a focused product launch. You address a known audience with clear, consistent materials, and you measure response state by state. That discipline keeps the raise clean and shortens your path to closing.Case Snapshots: Where Rule 504 Works
Consider a consumer food brand with a devoted regional following. The company has strong sales in two neighboring states and wants to invest in customers who ask about participating. Registering under Rule 504 in those states allows the brand to market within a known footprint. Because the audience already trusts the product, the message lands, and the brand can focus its budget on filings instead of national advertising. Another example is a small business services firm whose clients are concentrated within one metropolitan area. Their investors are primarily customers and partners. A targeted 504 effort allows the firm to share the opportunity ethically and coherently without scaling up a national compliance structure. A third scenario is a community real estate vehicle that aggregates investment into local projects. The value proposition is local knowledge and visibility. That is a natural use case for a state-registered offering that stays close to its base.Common Pitfalls and How to Avoid Them
Even well-prepared teams can stumble if they treat 504 like a generic Reg D raise. The most common missteps include drifting off script in marketing materials, underbudgeting state and filing fees, and assuming every state processes at the same pace. You can avoid those risks by setting internal controls for content, tracking a state-specific calendar, and making sure subscription, disclosure, and investor updates reflect the same set of terms. A short checklist can help you stay on track after you choose Rule 504:- Confirm which states you will file in and why those states align with your investor list.
- Lock approved language for marketing and investor communications and train the team.
- Map state timelines to your campaign calendar and hold to a weekly review cadence.
- Track commitments and funds by state, so post-close filings are complete and timely.
Choosing Rule 504 With Clarity
Rule 504 shines when your raise is modest, your investors are concentrated in a few states, and you can align marketing with state-reviewed materials. If you value speed, simplicity, and access to non-accredited investors in a focused footprint, 506(b) or Reg CF may be a better option. If your plan involves nationwide outreach, general solicitation, or a larger retail audience, you will usually find a better fit in 506(c), Reg CF, or Reg A. Match the exemption to your audience, geography, and timeline to avoid friction and rework. For tailored support with state securities filings and Reg D strategies, Blue Sky Comply can be contacted for related support.


Let Us Simplify Compliance for You
Partner with Blue Sky Comply to unlock seamless compliance, efficient filings, and access to expertise that lets you focus on your growth.
Schedule A Free Demo